Understanding Central Banks: A Comprehensive Guide
Central banks stand at the absolute center of modern financial architectures, operating as the ultimate guardians of monetary stability and economic order. These autonomous institutions are tasked with regulating national money supplies, calibrating benchmark interest rates, and restraining inflation. Their actions reverberate through every layer of society, shaping everything from commercial mortgage rates and corporate investment decisions to currency exchange values and the cost of daily groceries.
From their origins in seventeenth-century Europe to the sophisticated interventions demanded by twenty-first-century financial disruptions, central banks have evolved from basic state lenders into complex macroeconomic authorities. Understanding how these institutions operate, the tools they deploy, and the structural challenges they confront provides essential perspective on how global capital flows and why economies expand or contract.
Key takeaways
- Central banks manage national monetary supplies, establish benchmark borrowing costs, and preserve systemic financial stability.
- Institutions like the Federal Reserve, European Central Bank, Bank of Japan, and Bank of England set international liquidity trends that influence global markets.
- Primary conventional monetary tools include open market operations, reserve requirements, and discount window lending rates.
- When standard interest rate adjustments hit the zero lower bound, central banks utilize unconventional measures such as quantitative easing to support economic activity.
- Emerging frontiers like Central Bank Digital Currencies (CBDCs) and climate-related supply disruptions are reshaping traditional monetary frameworks.
The Evolution and Historical Foundations of Central Banking
The institutional model of modern central banking began taking shape during the seventeenth century. In 1668, Sweden established the Swedish Riksbank, widely recognized as the world's first central bank. Before the creation of centralized public monetary authorities, domestic banking systems were fragmented, with private commercial institutions frequently issuing their own banknotes backed by varying reserves of precious metals. This decentralized model led to frequent liquidity crises, uneven credit distribution, and bank runs that paralyzed local commerce.
Over the subsequent centuries, national governments recognized the necessity of maintaining an autonomous public authority dedicated to managing currency issuance and safeguarding financial stability. The transformation shifted these institutions from quasi-private state-chartered lenders into specialized regulatory bodies designed to serve the broader public interest. Modern central banks operate with clear mandates centered around two foundational pillars: interest rate determination and inflation management.
Adjusting short-term benchmark interest rates serves as the primary lever for guiding broad economic trends. When central banks increase interest rates, borrowing becomes more expensive for households and corporations, moderating consumer spending and slowing business expansion. Conversely, lowering interest rates stimulates borrowing, fuels capital investment, and encourages hiring. Managing inflation remains paramount because unchecked price increases rapidly erode consumer purchasing power, distort financial planning, and undermine confidence in domestic fiat currencies.
Core Responsibilities and Financial Stability Mandates
While interest rate management dominates financial news cycles, central banks are charged with structural responsibilities that sustain daily commercial transactions and reinforce system-wide financial architecture. Without these backstops, modern economies would remain vulnerable to sudden panics and liquidity freezes.
- Acting as a lender of last resort: During liquidity shortages or runs on private institutions, central banks supply emergency credit to solvent commercial banks against adequate collateral, preventing contagion across the banking network.
- Overseeing clearing and payment systems: Central banks operate and regulate core interbank settlement networks, guaranteeing that daily transactions, electronic transfers, and cheque clearings process without counterparty failure.
- Managing national currency distribution: Authorities oversee the physical production, distribution, and retirement of banknotes and coinage, while simultaneously tracking broad money aggregates circulating through commercial credit channels.
In recent decades, structural resilience has expanded to encompass macroprudential policy. Following repeated cross-border financial shocks, central banks recognized that focusing solely on consumer price indexes was insufficient to prevent financial meltdowns. Macroprudential policies target the health of the entire financial network rather than individual firms. Authorities now actively mandate countercyclical capital buffers for retail banks, establish upper limits on mortgage loan-to-value ratios to prevent real estate bubbles, and monitor systemic exposures across non-bank financial intermediaries.
Major Central Banks Shaping the Global Economy
Although virtually every sovereign nation maintains an independent monetary authority, an elite group of major central banks commands the overwhelming majority of global foreign exchange reserves and international debt markets. The decisions made inside their boardrooms dictate worldwide capital flows.
| Central Bank | Established | Headquarters / Jurisdiction | Primary Policy Objective |
|---|---|---|---|
| Federal Reserve | 1913 | United States | Dual mandate: price stability and maximum employment |
| European Central Bank | 1998 | Frankfurt, Germany (Euro Area) | Price stability across member states |
| Bank of Japan | 1882 | Japan | Price stability for sustainable economic expansion |
| Bank of England | 1694 | United Kingdom | Monetary and financial stability (2% inflation target) |
The Federal Reserve

- Established: 1913
- Statutory Mandate: Maximum employment, stable prices, moderate long-term rates
- Key Decision Body: Federal Open Market Committee (FOMC)
The Federal Reserve, commonly referred to as the Fed, was created by the United States Congress under the Federal Reserve Act of 1913. Unlike many unified foreign institutions, the Fed is a decentralized system comprising the Board of Governors in Washington, D.C., twelve regional Federal Reserve Banks, and the Federal Open Market Committee. The Fed operates under a statutory dual mandate requiring it to promote maximum employment alongside long-term price stability.
The Federal Open Market Committee serves as the Fed's primary policy organ, meeting regularly to determine the target range for the federal funds rate. Because the US dollar serves as the primary global reserve currency, decisions made by the FOMC directly impact international debt markets, exchange valuations, and cross-border trade settlements well beyond American borders.
The European Central Bank
- Established: 1998
- Headquarters: Frankfurt, Germany
- Key Decision Body: Governing Council
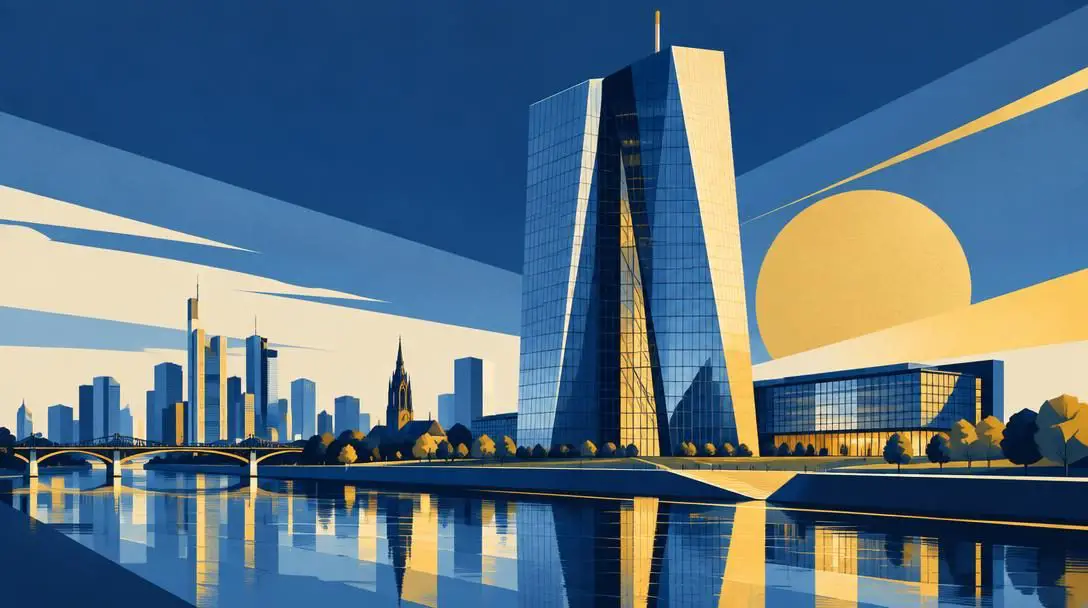
Headquartered in Frankfurt, the European Central Bank oversees monetary policy for the European Union member states that have adopted the single euro currency. Founded in 1998 ahead of the euro's formal rollout, the ECB is tasked with a primary treaty-bound mandate: maintaining price stability across the euro area. The institution coordinates foreign exchange operations, safeguards the official reserves of member nations, and works alongside national central banks within the Eurosystem.
Monetary strategy is governed by the Governing Council, composed of the six members of the Executive Board and the governors of the national central banks of member states. The Governing Council evaluates economic output and inflationary trends across multiple sovereign nations, adjusting key policy interest rates to maintain unified monetary coherence.
The Bank of Japan
- Established: 1882
- Headquarters: Tokyo, Japan
- Key Decision Body: Policy Board
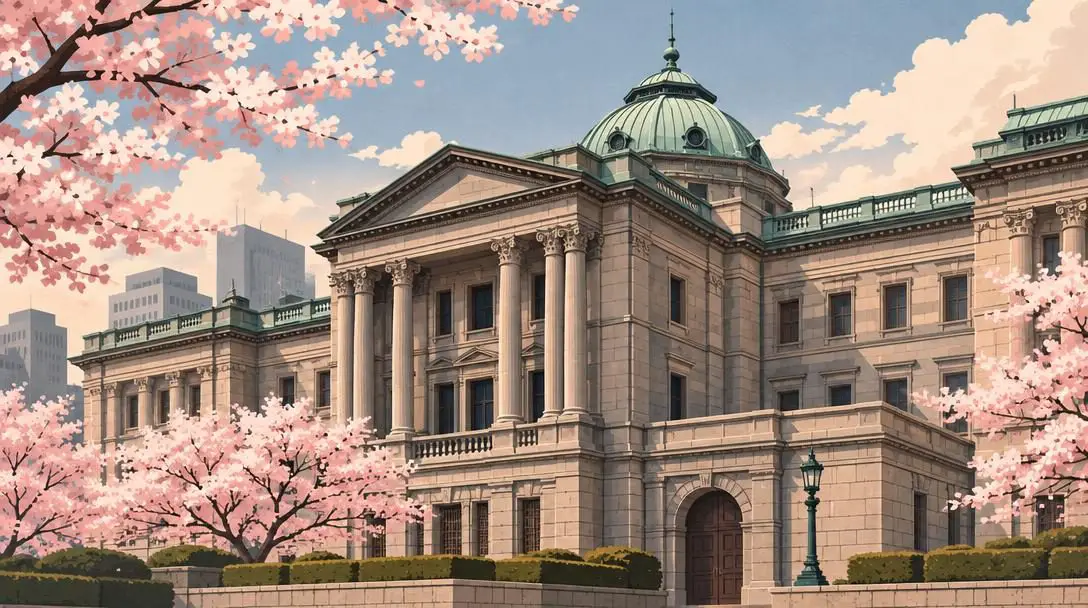
Founded in 1882, the Bank of Japan serves as the core monetary institution of the world's fourth-largest national economy. Its operational mandate focuses on maintaining price stability to provide a foundation for balanced, sustainable economic growth. The BoJ regulates the issuance of physical yen banknotes, oversees institutional liquidity, and carries out extensive surveillance over domestic financial institutions.
The central decision-making unit of the BoJ is the Policy Board, which consists of the governor, two deputy governors, and six outside appointed members. The Policy Board sets short-term interest rates and establishes asset purchasing policies that carry immense significance for sovereign bond markets and capital allocation patterns throughout the broader Asia-Pacific region.
The Bank of England
- Established: 1694
- Nickname: The Old Lady of Threadneedle Street
- Key Decision Body: Monetary Policy Committee (MPC)
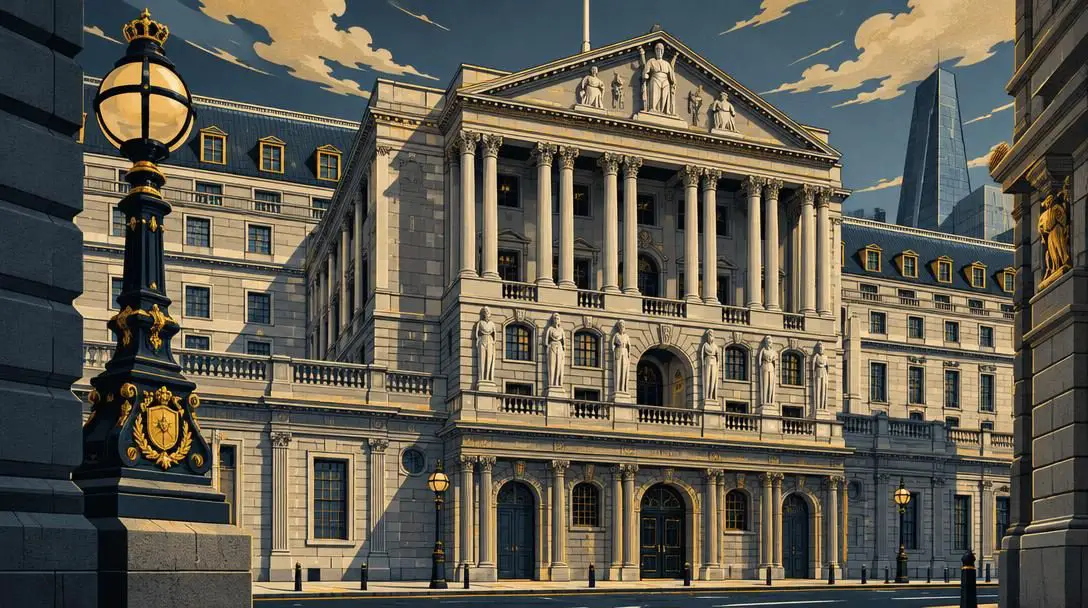
Originally chartered as a private financial institution to raise government funding during wartime in 1694, the Bank of England is one of the oldest monetary authorities in existence. Known informally as the Old Lady of Threadneedle Street, the modern institution acts as the central bank of the United Kingdom, tasked by the UK Government with maintaining monetary stability and preserving financial infrastructure.
The Bank of England's benchmark rate choices and asset purchases are set by its Monetary Policy Committee. The MPC operates under an explicit government mandate to achieve an annual consumer price inflation target of two percent. When inflation deviates significantly from this target, the governor must submit formal open letters to the Chancellor of the Exchequer detailing the causes and remedy schedules.
Monetary Policy Mechanisms and Implementation
To implement monetary strategy and influence national credit conditions, central banks rely on a standard toolkit of operational instruments. These core levers allow authorities to calibrate the availability and price of reserves inside commercial banking networks.
Open Market Operations
Open market operations represent the most frequent tool used by modern monetary authorities. In an open market transaction, a central bank buys or sells sovereign securities—such as treasury bills and sovereign bonds—in secondary capital markets. When an authority purchases government securities from primary dealers, it deposits electronic reserves directly into the banking system, increasing liquidity and pushing down short-term interest rates. Conversely, selling sovereign bonds extracts liquidity from commercial accounts, putting upward pressure on interest rates to tame inflationary demand.
Reserve Requirements
The reserve requirement establishes the minimum fraction of customer deposits that commercial institutions must maintain in reserve rather than deploying toward loans or investments. These funds are held either inside the bank's own vaults or as non-circulating deposits at the central bank. By raising reserve ratios, authorities force banks to retain more liquid collateral, which restricts broad lending capacity and contracts the domestic money supply. Lowering reserve requirements frees up balance sheet space, permitting commercial banks to issue credit more aggressively.
Discount Rate
The discount rate—often known as the benchmark lending rate or standing facility rate—is the interest rate applied to commercial banks that borrow short-term liquidity directly through the central bank's credit window. Access to this lending facility serves as a critical backstop during financial distress. When the central bank raises the discount rate, emergency borrowing becomes more expensive, prompting commercial lenders to adopt stricter credit standards. Lowering the rate encourages banks to lend freely, knowing that affordable short-term liquidity remains accessible if sudden depositors' demands arise.
Unconventional Policies and Quantitative Easing
During acute financial disruptions, standard operational tools can reach natural limits. When benchmark nominal policy rates fall close to zero—an impasse known as the zero lower bound—traditional rate cuts can no longer provide additional economic stimulus. Under these conditions, central banks turn to unconventional monetary strategies, with large-scale asset purchases taking center stage.
"Unconventional policies redefine the scope of monetary authorities, turning balance sheets into macroeconomic levers while presenting new structural risks."
Quantitative easing (QE) entails the massive direct purchase of longer-term financial assets, including long-dated sovereign bonds, mortgage-backed securities, and high-grade corporate debt. Instead of merely managing overnight bank rates, quantitative easing operates through distinct macroeconomic transmission channels:
- Depressing long-term borrowing yields: By purchasing significant quantities of long-maturity debt, central banks lower yields on sovereign debt, reducing commercial borrowing rates for corporate bonds and household mortgages.
- Triggering asset portfolio rebalancing: Lower yields on government securities compel private investors to seek returns in higher-risk assets, driving equity markets and lowering the cost of equity financing for expanding businesses.
- Generating wealth effects: Increased valuations across real estate and equity holdings lift consumer paper wealth, supporting household confidence and consumer spending during broader economic slowdowns.
- Delivering forward guidance: Large-scale balance sheet operations provide an unmistakable signal that policy rates will stay lower for longer, reducing interest rate uncertainty for corporate planners.
The Frontier: Central Bank Digital Currencies (CBDCs)
Technological transformation and the rapid growth of private digital assets have prompted central banks to explore the direct modernization of sovereign cash through Central Bank Digital Currencies. A CBDC represents an electronic, sovereign-backed expression of legal tender, existing directly as a liability of the central bank rather than a liability of a private commercial lender.
CBDCs carry potential structural benefits alongside complex operational risks:
- Streamlined transaction settlements: Wholesale CBDCs can accelerate cross-border foreign exchange payments, reducing clearance friction, transaction times, and administrative counterparty fees.
- Broadened financial inclusion: Retail CBDCs provide vulnerable or unbanked individuals direct access to sovereign digital payment tools without requiring conventional commercial bank accounts.
- Risk of bank disintermediation: If consumers can hold safe, interest-bearing deposits directly at the central bank, commercial banks face the threat of deposit flight during periods of economic instability.
- Cybersecurity and privacy challenges: Operating centralized digital currency platforms demands robust offline transaction resilience, strict defenses against state-sponsored cyberattacks, and delicate balancing between personal data privacy and regulatory compliance.
Future Challenges and Policy Trajectories
Central banks operate in an increasingly volatile global environment. The post-crisis era of ultra-low inflation and synchronized global supply chains has been challenged by geopolitical fragmentation, trade realignments, and demographic changes. Central bankers must continually balance the mandate of price stability against the looming danger of sparking deep recessions or compounding sovereign debt burdens.
Furthermore, climate-related disruptions are emerging as a major risk to traditional monetary forecasting. Severe weather disruptions, agricultural losses, and transitions away from carbon-intensive fuels introduce sudden supply-side price shocks that conventional demand-dampening interest rate hikes cannot resolve on their own. As public institutions holding extraordinary influence over modern societies, central banks face constant scrutiny to uphold their policy autonomy while operating within democratic accountability frameworks.
Frequently asked questions
What is the difference between a central bank and a commercial bank?
A central bank is a public authority responsible for managing national currency supplies, controlling inflation, and regulating the broader financial sector. It does not provide retail banking services or loans to individual consumers. A commercial bank is a profit-driven private institution that accepts consumer deposits, offers checking accounts, and issues mortgages and business loans.
How does raising interest rates help fight inflation?
When a central bank raises its benchmark interest rate, borrowing costs increase for commercial loans, credit cards, and mortgages. This higher cost of credit slows borrowing and dampens consumer spending and business capital investments, cooling aggregate demand across the economy and slowing the pace of price increases.
Why is the Swedish Riksbank historically significant?
Established in 1668, the Swedish Riksbank is recognized as the world's oldest central bank. Its founding established the structural precedent of a centralized public institution managing currency reserves and backstopping domestic credit stability.
What occurs when a central bank lowers its reserve requirements?
Lowering reserve requirements reduces the minimum fraction of customer deposits that commercial banks must hold in reserve. This frees up liquidity, expanding the banking sector's capacity to create new loans and increasing the overall domestic money supply.
What is the primary objective of the European Central Bank?
The primary statutory objective of the European Central Bank is maintaining price stability across the euro area member states that have adopted the single euro currency.
The bottom line
Central banks form the institutional backbone of the international monetary system. By balancing interest rate policies, managing systemic liquidity, and serving as unshakeable lenders of last resort, they safeguard the economic foundation that modern commerce depends on. As new obstacles emerge—from digital currency initiatives and fragmented supply chains to environmental shifts—the ability of central banks to adapt their operational tools while preserving monetary credibility will remain essential to long-term economic prosperity.