
5 Things You Need To Remember When Making Big Financial Decisions
Every person eventually reaches a pivotal crossroads where a single financial choice carries consequences that echo for decades. Major financial commitments do not present themselves every day, but when they do—whether purchasing a home, buying a new vehicle, entering the stock market, or signing a multi-year service agreement—vast sums of money are placed on the line. When hundreds of thousands of dollars are at stake, letting impulse guide your signature is one of the most hazardous moves a consumer can make.
Historically, personal finances operated against a more static backdrop. Generations past frequently entered the workforce with the expectation of remaining at a single enterprise until retirement, a stability that fostered predictable, linear financial planning. Today, that economic model is gone. Modern professionals navigate a fluid employment landscape, changing employers and locations to secure higher compensation. This professional mobility demands a far more strategic, calculated approach to long-term financial obligations before entering any binding contract.
Key takeaways
- Separate absolute life essentials from lifestyle luxuries to avoid overextending your budget on unnecessary upgrades.
- Never deplete your entire cash reserve for a transaction; ensure a substantial savings cushion remains to earn interest and preserve security.
- Always secure competing quotes and negotiate terms rather than accepting the initial price offered by a seller or lender.
- Align major contractual commitments with your three-to-five-year professional trajectory and geographic mobility plans.
- Pay down existing credit card and loan balances before seeking major financing to safeguard your credit score and unlock favorable interest rates.
The Modern Economic Reality and Long-Term Commitments
Decades ago, career paths tended to follow an uninterrupted trajectory. Workers often spent their entire adult lives at a single firm, receiving steady raises and retiring with a predictable pension. That level of lifelong employer predictability gave people the confidence to sign long-term financial contracts without worrying about sudden geographic or professional disruption.
In the contemporary economy, that predictability has been replaced by rapid career mobility. Professionals frequently change employers, take on new responsibilities, and even relocate across states or countries to pursue enhanced compensation. While moving between companies can accelerate earnings, it also introduces operational complexity into personal finances. Entering a rigid, long-term financing agreement without evaluating career flexibility can restrict your choices, effectively tying you to an employer or a city when better prospects emerge elsewhere.
When hundreds of thousands of dollars might be in play, making an impulse decision is one of the most dangerous moves you can make.
Signing any legal paperwork binds you for an extended duration. Taking a deliberate step back to review your foundational obligations, liquid reserves, career horizon, and current liabilities ensures that every contract you sign supports your broader goals rather than producing chronic economic strain.
Five Foundational Principles for Big Financial Decisions
Before agreeing to terms on any major purchase or investment, you must systematically review your financial footing. The following five principles serve as the bedrock for evaluating whether a major commitment is genuinely sustainable.
| Principle | Primary Focus | Key Risk Avoided |
|---|---|---|
| Distinguish Wants from Needs | Isolating baseline requirements from non-essential luxuries | Overpaying for cosmetic features or excessive square footage |
| Examine Your Savings Account | Maintaining post-transaction cash cushions and yields | Exhausting liquidity and losing compounding interest |
| Shop Around and Compare Prices | Generating leverage through competitive bids and negotiation | Accepting unfavorable terms or inflated introductory pricing |
| Evaluate Your Long-Term Career Path | Aligning debt and ownership with future geographic moves | Restricting professional growth and job mobility |
| Review Your Existing Debt Profile | Clearing revolving balances before adding obligations | Damaging credit ratings and absorbing compounding interest |
Distinguish Wants from Needs
Human survival depends on four core necessities: food, water, clothing, and shelter. Among these four fundamental needs, shelter is almost always the only one that represents a massive, capital-intensive financial choice, though high-end clothing can occasionally command steep prices as well. When shopping for real estate, buyers often blend their practical requirements with aspirational lifestyle preferences, creating an expensive mismatch between what they need and what they buy.
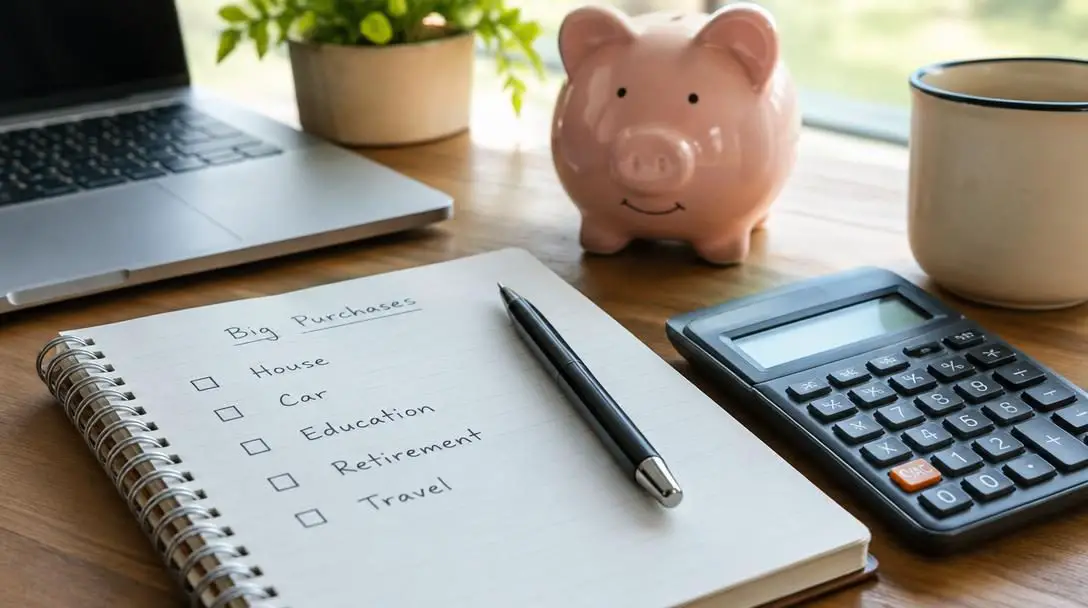
It is vital to maintain realistic expectations and shop strictly within your means. For instance, home shoppers should candidly evaluate whether an expansive floor plan with multiple spare bathrooms is a functional requirement or an overpriced luxury that inflates the mortgage. This disciplined mindset must govern every category of spending. Not every dinner demands a five-course spread, and daily clothing choices do not need to feature luxury designer labels. By establishing firm boundaries between essential shelter and discretionary upgrades, you keep your commitments reasonable.
Examine Your Savings Account
Savings accounts are built specifically to equip individuals for large capital outlays and unforeseen disruptions. Leaving surplus funds inside an everyday checking account is often counterproductive, as accessible balances are easily chipped away by casual, impulse spending. Instead, sound financial management requires moving a designated portion of every paycheck directly into a dedicated savings vehicle as soon as routine bills are resolved.
Consistent deposits enable a cash reserve to compound over time, capturing interest yields that grow increasingly valuable as the principal expands. Before agreeing to a major purchase, review your overall savings balance with a critical eye. A transaction is truly affordable only if you can settle the purchase price or down payment while still leaving a healthy cash reserve in the account to preserve your safety net and continue generating interest earnings.
Shop Around and Compare Prices
When entering the market for high-ticket assets such as real estate or automobiles, accepting the initial price tag presented by a dealer or seller is rarely advantageous. The very first price you encounter is almost never the most competitive deal on the market, and in many instances, it turns out to be the least favorable arrangement available. Buyers who leap at the first number forfeit their primary economic advantage: competition.
Taking the time to investigate alternatives across multiple sellers creates immediate leverage. In transactions involving houses and motor vehicles, list prices are routinely flexible, leaving room for active negotiation. When sellers and dealerships understand that they are competing against other market options for your capital, the buyer gains the upper hand, allowing you to haggle terms downward into a much more favorable pricing bracket.
Evaluate Your Long-Term Career Path
Because today's workforce relies on career mobility to secure higher salaries and professional advancement, your personal balance sheet must reflect your expected employment trajectory. Before signing agreements that bind your income for years or decades, project where your professional life is headed over a multi-year horizon.
Ask yourself whether you expect to remain in the same role, continue working for the same company, or stay within the same metropolitan area over the next few years. If your trajectory involves moving to a competing firm or relocating to another city for higher pay, entering into an inflexible local purchase or acquiring a massive long-term loan could complicate your ability to act when attractive career prospects present themselves.
Review Your Existing Debt Profile
A widespread financial misconception is that regularly paying the monthly minimums on credit cards and existing auto loans indicates a green light to take on fresh liabilities. Managing existing monthly minimums does not equal financial capacity for new debt. Layering a major new financing obligation on top of an already leveraged profile can trigger significant financial consequences.
Taking on an additional major loan can prompt an abrupt drop in your credit score, while combined monthly obligations frequently turn out to be far higher than anticipated. As interest compounds across separate balances, debt servicing can become unmanageable. Ideally, an individual's balance sheet should be largely free of debt before taking on a new obligation. Mortgage providers and institutional lenders reserve their most competitive rates for borrowers who maintain open credit lines but do not actually carry balances on them.
Step-by-Step Decision-Making Framework
Navigating significant purchases demands a structured framework that strips emotion out of the equation. Following a consistent sequence of checks and balances ensures that your choices are based on objective affordability rather than high-pressure sales pitches.
- Separate necessities from discretionary add-ons: Draft an itemized list of must-have features versus luxury upgrades before browsing showrooms or listings. For home purchases, prioritize commute times, safety, and adequate space over high-end finishes and excess bathrooms.
- Automate regular post-bill savings: Set up automated transfers so that surplus funds move into interest-earning savings accounts immediately after monthly expenses are cleared, keeping money out of checking where it is easily spent.
- Establish a remaining cash floor: Calculate the minimum cash threshold that must remain untouched in your liquid savings after down payments or closing costs are deducted. If a deal breaches that floor, postpone the transaction.
- Collect multiple competing quotes: Approach several competing vendors, dealerships, or lenders to gather written terms. Use the presence of multiple market options as a bargaining tool to negotiate the purchase price downward.
- Conduct a multi-year career audit: Evaluate your three-to-five-year professional plan to ensure that purchasing an asset will not compromise your ability to switch employers, accept promotions, or relocate for better compensation.
- Pay down open credit balances: Lower your credit utilization by paying off revolving credit cards and smaller personal loans prior to seeking major financing, which strengthens your credit profile for better lending terms.
Common Financial Pitfalls to Avoid
Even conscientious buyers can fall into preventable traps when navigating substantial financial choices. Keeping these frequent errors in mind will safeguard your balance sheet from avoidable harm.
- Rationalizing wants as baseline needs: It is easy to convince yourself that luxury amenities are functional requirements. High-end finishes, designer apparel, and gourmet dining choices are personal preferences, not survival necessities. Overspending on non-essentials unnecessarily inflates your loan balances.
- Emptying your emergency reserves: Possessing sufficient cash in an account to complete a purchase does not mean the asset is truly affordable. When a purchase leaves an account with zero balance, your financial security net disappears, and you lose ongoing interest gains.
- Surrendering to sales pressure on the first quote: Accepting introductory terms without exploring competing alternatives is a costly mistake. The initial price offered by a seller or lender is rarely the best deal and often proves to be the most expensive option available.
- Layering new debt over active balances: Assuming that meeting minimum monthly payments qualifies you for additional loans is a dangerous oversight. Stacking loans increases cumulative interest, inflates monthly liabilities beyond expectations, and can damage your credit score.
Frequently asked questions
How much money should remain in a savings account after a major purchase?
A major transaction should never wipe out your cash reserves. You should only finalize a big purchase if you can comfortably pay the required costs while still leaving plenty of funds behind in your account to preserve your safety cushion and continue capturing interest yields.
Why is carrying existing debt problematic if minimum payments are made on time?
Simply managing monthly minimums on credit cards and existing auto loans does not mean you have the capacity for new debt. Adding another major liability can cause your credit score to drop sharply, lead to unexpectedly high cumulative payments, and trigger an overwhelming accumulation of interest charges across multiple accounts.
How does career mobility influence long-term financial commitments?
Modern workers frequently switch companies or relocate to secure higher compensation. Committing to a massive local purchase or an inflexible long-term loan can anchor you to a specific employer or city, potentially limiting your ability to pursue higher-paying career opportunities elsewhere.
Why is accepting the first price offered on a house or car a mistake?
The initial price presented by a dealer or seller is rarely the best offer available and is often the worst. Major assets like vehicles and houses generally have room for negotiation, and obtaining multiple quotes forces competing sellers to lower their prices to win your business.
What is the difference between needs and wants when purchasing a home?
Shelter is a basic survival necessity, but luxury add-ons are preferences. A need encompasses functional shelter that fits your budget, whereas wants include non-essential luxuries such as extra spare bathrooms, high-end designer finishes, or expansive floor plans that inflate the total price tag.
The bottom line
Major financial commitments carry implications that extend far beyond the day contracts are signed. Entering into a substantial purchase requires a clear assessment of your actual requirements, a protected savings cushion, and an awareness of competitive pricing across the market. Rather than rushing into agreements based on emotion or introductory sales offers, pause to review your current debt levels and projected professional path.
By clearing outstanding debt balances, keeping your savings account actively growing with interest, and ensuring your obligations match your career aspirations, you maintain complete control over your economic trajectory. Strategic preparation turns major financial milestones into long-term assets rather than ongoing sources of financial strain.




