Assessing Your Risk Tolerance Before Investing in Stocks: 5 Questions To Ask Yourself
Investing in the stock market offers significant potential to build long-term wealth, but it inherently requires navigating uncertainty. Because share prices constantly fluctuate based on macroeconomic shifts, company-specific updates, and broader market sentiment, every investor must confront the reality of potential losses. Determining your risk tolerance—the degree of variability in investment returns you are willing and able to withstand—is the foundational step in designing a sustainable investment strategy.
Too many individuals enter equity markets focused exclusively on upside gains, only to discover their true emotional limits when market turbulence arrives. Without an accurate assessment of risk tolerance, normal price swings can trigger panic, prompting investors to sell assets at a steep loss. By evaluating both your emotional appetite for market fluctuations and your practical capacity to absorb financial declines, you can build a resilient portfolio tailored to your unique financial trajectory.
Key takeaways
- Risk tolerance combines your emotional willingness to endure short-term losses with your practical financial capacity to absorb them.
- A longer holding period provides a buffer against cyclical downturns, allowing companies time to grow and share values to recover.
- Evaluating individual stocks requires examining business fundamentals, corporate leadership, and specific vulnerabilities like liquidity and sector volatility.
- Clear financial goals dictate whether an investor should prioritize capital preservation, recurring dividend income, or aggressive long-term appreciation.
- Assessing risk is an ongoing process that requires periodic portfolio rebalancing and adjustments whenever major life events alter your timeline.
The Anatomy of Risk Tolerance: Emotional Willingness vs. Financial Capacity
Risk tolerance is not a static or generic number. It is deeply personal, shaped by psychological comfort, tangible financial resources, and the time remaining before you need your invested capital. When breaking down how risk tolerance functions in an investment portfolio, financial planners look at two distinct but interdependent pillars: emotional willingness and financial capacity.
Emotional willingness reflects your psychological reaction to market swings. If checking your investment account during a downturn causes intense anxiety or sleepless nights, your emotional tolerance for risk is relatively low. Investors with lower psychological tolerance are typically better served by stable, conservative holdings that experience modest fluctuations. Conversely, investors who can calmly watch their paper portfolio balances drop without feeling an uncontrollable urge to liquidate possess a higher emotional risk tolerance.
Financial capacity, on the other hand, is an objective assessment of whether you can afford to absorb a financial loss without derailing your day-to-day living expenses or long-term solvency. Regardless of how calm you feel during a downturn, your actual capacity to take on risk is governed by external realities, including your emergency reserves, household income stability, overall net worth, and your investing timeline. If you require access to invested cash within months, your financial capacity for risk is minimal, regardless of your personal bravery.
Risk tolerance represents the boundary between an investment strategy that lets you sleep at night and one that forces you out of the market at the worst possible time.
Risk and Return Across Major Asset Classes
Every investment decision involves a direct trade-off between risk and reward. Assets that offer the potential for higher long-term capital gains—such as individual shares of stock—inevitably experience greater price volatility and expose the investor to a higher probability of capital loss. More conservative instruments, such as fixed-income securities, generally display lower volatility and offer greater principal stability, though they deliver lower overall returns over extended periods.
| Asset Class | Volatility Level | Primary Risk Profile | Typical Role in Portfolio |
|---|---|---|---|
| Individual Stocks | High to Very High | Business failure, price swings, market downturns | Long-term capital growth and dividend income |
| Mutual Funds | Moderate to High | Market risk, sector exposure, underlying asset declines | Diversified equity or bond exposure with pooled risk |
| Bonds | Low to Moderate | Interest rate shifts, inflation, borrower default | Capital preservation, income generation, and stability |
The 5 Essential Questions to Ask Yourself Before Buying Stock
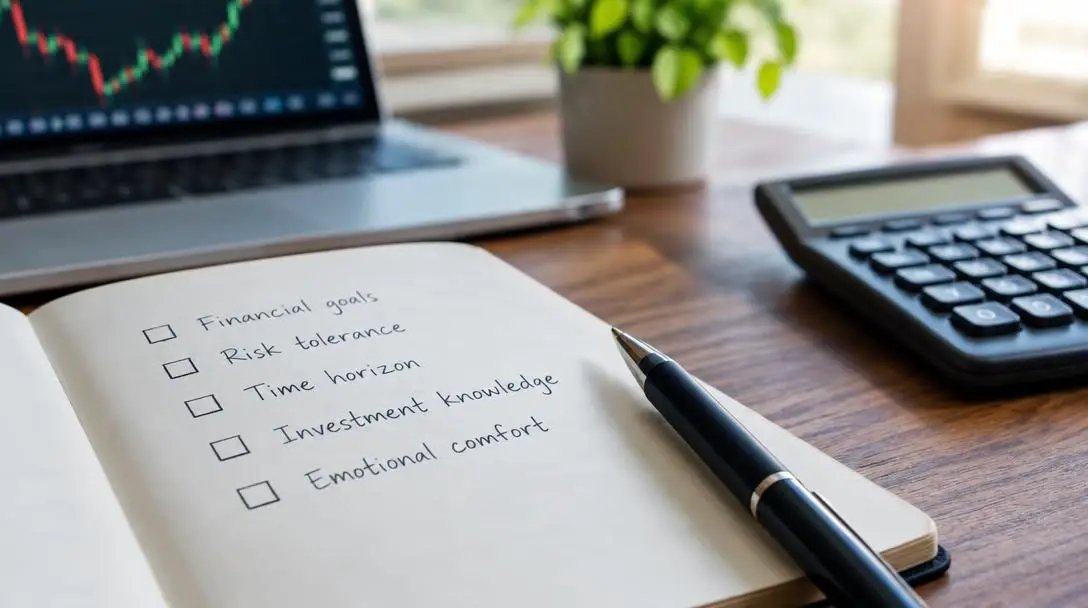
Before allocating capital to any individual equity position, take the time to answer five foundational self-assessment questions. These prompts clarify your risk appetite, identify hidden hazards, and ensure every investment matches your overarching financial objectives.
1. How Much of an Investment Loss Would You Realistically Be Able to Tolerate?
Market volatility is an inescapable reality of equity investing; share prices drop on a regular basis. You must determine the specific loss threshold you can stomach before you feel overwhelmed. If losing even a small portion of your principal on a given trade creates unmanageable stress, individual stocks may not be suitable for your primary holdings. In that scenario, more stable instruments like mutual funds and bonds provide a much safer foundation. If you are comfortable absorbing price drops in exchange for higher upside, equities can help diversify your holdings and increase potential returns. Setting a clear boundary prevents you from taking on more turbulence than you can emotionally and financially manage.
2. How Long Do You Plan on Holding Onto Any Given Stock?
Your intended investment timeframe—known as your time horizon—directly dictates the amount of risk you can prudently assume, as well as your prospective return on investment. Time functions as a crucial shock absorber against short-term market downturns, granting underlying businesses the runway to compound earnings, innovate, and recover from cyclical corrections. If you expect to hold a stock for only a few weeks or months, a sudden price drop can permanently lock in painful losses if you are forced to exit. Longer holding periods allow you to benefit from compounded dividend payments and long-term capital appreciation while riding out routine market fluctuations.
3. What Types of Risks Are Involved With Any Given Stock?
No two companies carry the exact same risk profile, and broad stock classifications can obscure significant individual vulnerabilities. Evaluating a stock requires dissecting three primary hazards:
- Volatility Risk: Rapid, sharp swings in price over compressed intervals, which dramatically elevate short-term capital risk.
- Liquidity Risk: Lower trading volumes that make buying or selling large share quantities at your preferred price difficult without artificially distorting the market quote.
- Market and Sector Risk: The vulnerability of a specific industry to political unrest, regulatory changes, international trade barriers, or broad economic downturns.
4. How Well Do You Understand the Company Behind the Stock?
A stock is not merely a fluctuating ticker symbol; it represents an actual fractional ownership stake in an active business enterprise. To accurately judge an investment's risk, you must evaluate the company's core operational model, its competitive strengths, and the broader trends impacting its industry. Equally critical is assessing the corporate structure and the caliber of the executive management team. Capable, ethical corporate leadership can navigate complex disruptions and preserve shareholder capital, whereas poor management can destroy value and worsen losses even in favorable macroeconomic environments.
5. What Are My Overall Financial Goals?
Investing without clear objectives makes it virtually impossible to calibrate how much risk is necessary or acceptable. Every asset in your portfolio should serve a deliberate purpose. An investor striving for regular, recurring income to supplement immediate living expenses will select dramatically different assets than someone pursuing multi-decade capital compounding or pure wealth preservation. Establishing your financial goals clarifies which stocks fit your strategy and prevents you from taking uncalculated risks that offer no strategic benefit.
Practical Steps to Align Your Portfolio With Your Risk Profile
Translating self-reflection into a concrete investment portfolio requires a structured, repeatable process. Work through these sequential steps before deploying capital into the market:
- Write down your specific financial goals: Document exactly what you are saving for, the exact target amounts, and the dates when you will need to access the capital.
- Examine your overall asset allocation: Verify that your broad asset split reflects your capacity for loss. If your risk tolerance is low, ensure adequate weighting in bonds and mutual funds; if your horizon is long and your appetite for risk is robust, maintain sufficient equity exposure to drive capital appreciation.
- Research individual companies thoroughly: Scrutinize the business model, corporate governance structure, balance sheet health, and management track record for every individual company on your watchlist.
- Identify specific stock-level risks: Review each prospective holding for elevated volatility, illiquidity, and exposure to sector-wide recessions or geopolitical shifts.
- Establish clear exit and holding rules: Define your holding timeline in advance so you are not tempted to abandon solid assets during standard market pullbacks, and ensure speculative short-term trades are closed out rather than held indefinitely.
Common Pitfalls That Distort Risk Tolerance
Even seasoned investors frequently fall prey to psychological traps that lead to miscalculated risk. Staying mindful of these common missteps will protect your portfolio from unforced errors:
- Overestimating risk tolerance in bull markets: When equities march steadily upward, investors routinely convince themselves that they can stomach severe drawdowns. Genuine risk tolerance is only tested during prolonged, painful market sell-offs.
- Confusing short-term trading with long-term investing: Day trading or flipping stocks requires entirely different risk controls than long-term investing. Short windows eliminate the compounding power of business operations and dividend payouts, leaving you completely exposed to short-term market noise.
- Ignoring company fundamentals: Buying shares based on hype, social media buzz, or momentum without understanding the operational mechanics or management team leaves you blindsided when business conditions sour.
- Overlooking sector-specific vulnerabilities: Concentrating capital in an industry heavily vulnerable to regulatory scrutiny, economic downturns, or geopolitical friction can wipe out portfolio gains during unexpected headwinds.
- Investing without defined targets: Allocating money without a clear destination makes measuring performance impossible and frequently causes investors to take excessive risks out of boredom or excessive caution out of vague fear.
Maintaining and Updating Your Risk Strategy
Assessing risk tolerance is not an isolated, one-time exercise. As your life unfolds, your economic circumstances, earning capacity, and personal commitments will shift, requiring corresponding adjustments to your portfolio.
First, schedule periodic portfolio checkups. Over time, higher-performing individual stocks will naturally expand as a percentage of your total wealth, inadvertently shifting a conservative portfolio into an aggressive one. Periodic rebalancing restores your holdings to the target allocation that fits your genuine comfort level.
Second, update your risk assessment whenever major life events take place. Career transitions, marriages, unexpected changes in household income, or nearing retirement will alter your investment horizon and reduce your capacity to absorb paper losses. As your window to recover from market shocks shrinks, prudently trimming volatile individual stocks in favor of conservative assets like bonds and mutual funds preserves your hard-won capital.
Frequently asked questions
What is the difference between risk tolerance and risk capacity?
Risk tolerance is your emotional and psychological willingness to endure price drops without panicking, whereas risk capacity is your mathematical, financial ability to withstand losses without jeopardizing your lifestyle, emergency funds, or immediate financial commitments.
Can my risk tolerance change over time?
Yes. Your risk tolerance naturally evolves as you age, as your career or household income changes, and as you get closer to the date you need to withdraw your funds. Major life transitions necessitate updating your investment strategy.
Are mutual funds safer than individual stocks?
Mutual funds are generally considered lower risk than individual stocks because they hold a diversified basket of underlying investments. This pooled structure prevents a decline or failure in a single company from wiping out your entire investment.
How does my investment time horizon affect my risk tolerance?
A longer time horizon increases your risk capacity by giving your portfolio the necessary time to ride out cyclical downturns and recover from market corrections. A short horizon requires lower risk because an unexpected price crash can lock in permanent financial losses.
What should I do if I find out my portfolio is too risky for me?
If you experience persistent stress or anxiety during market dips, rebalance your asset allocation. You can reduce your overall volatility by trimming volatile individual stocks and allocating a larger percentage of your money to stable holdings such as bonds or broad mutual funds.
The bottom line
Investing in stocks is one of the most reliable vehicles for generating long-term wealth, but success requires staying invested through both economic expansions and sharp downturns. By rigorously evaluating your emotional reactions, financial capacity, investment horizon, and fundamental knowledge of the companies you own, you can craft an asset allocation that protects your peace of mind while steadily compounding your capital.