
Strategies to Pay off Debt Quickly
Carrying debt can feel like a heavy weight, threatening household stability and narrowing personal choices. However, debt is not a permanent condition; it is a financial circumstance that can be systematically dismantled. At its core, debt occurs whenever money is borrowed with an agreement to repay it later alongside additional fees known as interest. When balances remain unpaid across months or years, these recurring financing fees compound, absorbing an ever-larger portion of monthly earnings and leaving fewer resources for basic living costs, unexpected emergencies, and future goals.
Regaining control requires understanding how interest charges interact with your loan balances. When you make only the minimum required payment, lenders allocate a substantial portion of those funds toward covering accrued interest rather than reducing the initial amount borrowed. This keeps your principal balance elevated, which in turn triggers another steep interest assessment during the subsequent billing cycle. Breaking free from this cycle demands an organized plan that targets the principal directly, redirects household cash flow, and eliminates liabilities step by step.
Key takeaways
- Targeting balances with the highest interest rates first yields the greatest long-term savings by removing the costliest financing fees.
- Directing extra payments specifically toward the principal balance reduces future interest charges and significantly speeds up loan payoff.
- Constructing a lean operating budget creates the necessary monthly surplus to attack debt aggressively.
- Contacting lenders to negotiate lower interest rates or modified terms can instantly redirect more of each payment toward the principal.
The Underlying Mechanics of Debt and Compound Interest
To clear outstanding balances efficiently, you must first examine how borrowing costs accumulate. When a financial institution issues a credit card, personal loan, or auto financing agreement, it charges interest calculated as a percentage of your outstanding principal balance. Every month you carry that balance forward, the creditor applies this percentage fee. When debtors submit only the baseline minimum payment, the lender takes the financing charge off the top, leaving only a tiny fraction to reduce the actual balance owed.
Because the principal barely moves under a minimum-payment schedule, the subsequent month's interest charge is calculated against an almost identical balance. This repetitive pattern keeps borrowers in repayment for years, and in some cases decades, paying multiples of what they originally borrowed. Reclaiming financial independence means transforming how money moves through your household each month. Eliminating balances frees up vital cash flow that can eventually fund personal savings, retirement investments, and long-term security, permanently lifting the stress of unpaid accounts.
Every dollar diverted away from accumulated financing charges is a dollar that directly accelerates your journey out of debt.
Five Strategic Levers to Speed Up Debt Repayment
Becoming debt-free does not happen by accident. It requires deliberate tactics designed to dismantle balances while protecting your household from slipping backward. The following core strategies establish the framework for rapid debt elimination.
1. Prioritizing High-Interest Balances First
When juggling multiple debts, the order in which you pay them off determines how much the process will ultimately cost. You should always prioritize accounts that carry the highest interest rates, as these represent your most expensive liabilities. By tackling high-rate accounts first, you immediately curb the growth of costly financing fees and accelerate your overall progress.
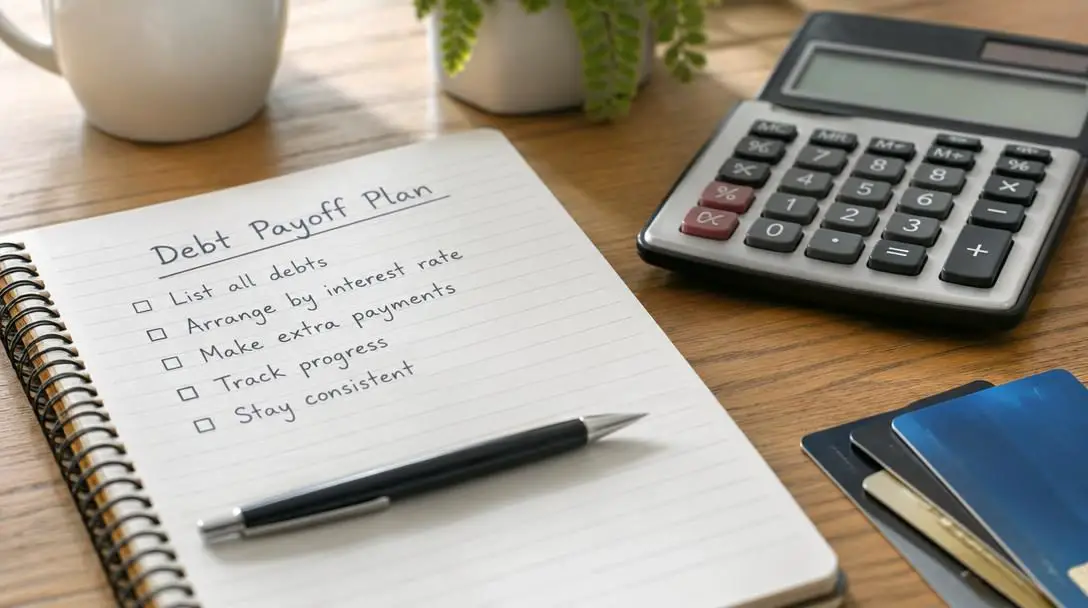
Begin by listing every active balance alongside its corresponding interest rate. Identify the single account with the steepest rate—often a retail card or high-interest credit card. While continuing to make required minimum payments on every other account to keep them in good standing, channel every surplus dollar toward this single target. Once that balance hits zero, take the entire monthly sum you were paying toward it and redirect it to the account with the next highest interest rate. This rollover approach keeps your repayment momentum expanding while the total number of open balances declines.
2. Building and Managing a Focused Operating Budget
A practical budget acts as an operational roadmap for your money, eliminating uncertainty from daily decisions. Developing an accurate monthly budget reveals your baseline spending patterns and ensures that every routine obligation is satisfied on time. More importantly, it highlights discretionary spending that can be pruned to channel extra capital toward balances.
To establish an effective budget, tally all monthly net income against mandatory survival expenses, including housing, utilities, basic groceries, transportation, and current minimum debt obligations. The difference between your total net income and mandatory expenses represents your debt-fighting surplus. Scrutinize recent bank statements for non-essential outflows such as recurring subscriptions, dining out, and impulse shopping. Trimming these discretionary expenses is not a permanent deprivation; it is a temporary, strategic trade-off that rapidly builds the surplus needed to eliminate what you owe.
3. Channeling Targeted Extra Payments to Principal
Submitting extra payments beyond the mandatory minimum is one of the most reliable ways to expedite your exit from debt. Minimum payments are calibrated by lenders to extend the duration of a loan, maximizing their interest earnings. By sending extra funds, you bypass unnecessary interest and strike directly at the core balance.
Lowering the principal immediately shrinks the base upon which all future interest is calculated. As a consequence, subsequent monthly interest fees drop, enabling a greater share of your baseline payment to chip away at the principal. Extra payments do not have to be massive windfalls. Submitting bi-weekly payments, allocating small cash surpluses throughout the month, or applying modest bonuses consistently compounds into significant time saved off your repayment timeline.
4. Negotiating Directly with Creditors for Lower Rates
Many creditors are open to adjusting terms when borrowers initiate a candid conversation. If you are weighed down by high-interest rates, proactively reaching out to your lenders can yield lower annual percentage rates (APRs) or longer, structured payment plans. A lower rate ensures that a far greater percentage of every dollar paid goes toward knocking down the principal rather than feeding interest charges, potentially saving thousands over the life of the debt.
Lenders frequently prefer negotiating realistic terms over having an account enter delinquency or default. Prepare for these conversations by having your account numbers, current interest rates, and payment history ready. Clearly explain your desire to clear the balance, request a rate reduction or hardship program, and take detailed notes during the call. Record the representative's name, the date, and the specific terms discussed, and always request written confirmation of any newly adjusted arrangement.
5. Structuring Measurable Short-Term Milestones
Staring at a large cumulative debt total can be mentally draining, leading to fatigue and loss of focus. Establishing specific, measurable financial goals breaks an intimidating total balance into manageable, near-term targets. Defining milestones keeps your motivation sharp and provides objective benchmarks to verify that your efforts are yielding results.
Rather than obsessing over the entire mountain of debt, establish intermediate checkpoints. For example, set a goal to pay down a specific card within 90 days or reduce total principal by a predetermined dollar figure before the end of the quarter. Track these achievements using spreadsheets, visual charts, or dedicated checklists. Celebrating the completion of each milestone—using low-cost or free rewards—reinforces the daily financial discipline needed to see the entire process through to the end.
Comparing Core Debt Payoff Levers
Every tactic plays a distinct role in your broader repayment strategy. Understanding how each lever operates allows you to combine them for maximum efficiency.
| Repayment Lever | Primary Mechanism | Immediate Financial Benefit | Key Implementation Challenge |
|---|---|---|---|
| High-Rate Prioritization | Orders accounts by APR, attacking the costliest first | Minimizes total financing charges over time | Requires patience when the highest balance is large |
| Extra Principal Payments | Applies surplus cash directly to principal debt | Instantly lowers the base used to calculate interest | Demands consistent monthly cash flow discipline |
| Rate Negotiation | Lowers contractual APR via direct creditor discussions | Increases the principal impact of every standard payment | Requires proactive communication and recordkeeping |
| Budget Optimization | Cuts non-essential expenses to create cash surplus | Maximizes the funds available to direct toward debt | Requires temporary reductions in discretionary spending |
A Step-by-Step Implementation Framework
Executing an effective debt payoff strategy requires an orderly approach. Follow this systematic workflow to move from disorganized balances to steady, predictable progress.
- Compile your complete debt inventory: Gather current statements for every outstanding obligation. Document the creditor's name, total principal balance, minimum monthly payment, and active interest rate in a single document or sheet.
- Order your debts by interest rate: Sort your list in descending order, placing the account with the highest interest rate at the top, down to the account with the lowest rate at the bottom.
- Audit your monthly income and expenses: Review bank and card statements from the past two to three months. Categorize every transaction into essential baseline obligations versus non-essential spending.
- Establish a lean operating budget: Set firm caps on discretionary categories. Eliminate recurring subscriptions, pause non-critical retail purchases, and curtail dining out to generate immediate surplus cash each month.
- Automate your minimum obligations: Schedule automatic minimum payments on every account except the top-priority, highest-interest account. This protects your credit standing and prevents late fees.
- Contact your creditors directly: Call your lenders to request reduced interest rates or inquire about structured payoff concessions, emphasizing your commitment to repaying the balance.
- Channel surplus funds to your top priority: Apply every available dollar—including budgeted surplus and any variable income—directly toward the principal of the highest-interest account.
- Review and adjust monthly: Re-examine your budget at the end of each billing cycle. As balances disappear, roll those freed-up minimums and surplus funds directly into the next highest-rate account on your list.
Common Pitfalls That Threaten Debt Repayment
Even motivated borrowers can encounter obstacles that slow down progress or reverse hard-earned gains. Recognizing these common traps helps you maintain continuous forward momentum.
- Relying solely on minimum payments: Treating minimums as sufficient repayment guarantees you will spend years paying interest rather than erasing what you actually borrowed.
- Operating without an active budget: Assuming you can track spending mentally leads to unmonitored cash leaks that absorb funds meant for debt elimination.
- Neglecting to negotiate terms: Believing interest rates are set in stone leaves substantial cost savings on the table; many creditors are willing to lower rates when asked.
- Failing to track incremental milestones: Looking only at the overarching total can cause discouragement; tracking smaller, interim targets sustains your focus.
- Misallocating extra payments: Submitting additional funds without instructing the lender to credit them directly to the principal can result in funds being treated as prepayments on future interest.
Frequently asked questions
Why is it better to pay off high-interest debt first?
Debts with the highest interest rates cost you the most money for every dollar borrowed. By eliminating them first, you stop the accumulation of costly financing fees and reduce total interest expenses, allowing more of your money to directly lower your balances.
How do extra payments shorten the time it takes to get out of debt?
Extra payments directed to the principal instantly lower the base balance used to calculate subsequent interest charges. When future interest drops, a larger percentage of every normal monthly payment goes directly toward paying down principal, accelerating the payoff schedule.
What should I do if a creditor refuses to lower my interest rate?
If an initial request is declined, politely ask to speak with a supervisor or inquire about formal hardship programs. If the rate remains fixed, keep that account in your structured repayment plan, continue paying minimums, and tackle it strictly in order of its interest rate ranking.
Should I stop saving money completely while paying off debt?
While the bulk of your surplus cash should target high-interest principal, maintaining a lean budget for baseline living costs prevents you from relying on new credit when unexpected expenses arise. Once high-interest balances are eliminated, that cash flow can be pivoted toward an emergency fund.
How can I make sure extra payments are applied to principal?
Check your lender's online portal for a payment distribution setting, such as a checkbox indicating 'Principal Only' for excess funds. If that option is absent, call your servicer directly to confirm that extra payments reduce the balance rather than advancing next month's due date.
The Bottom Line
Eliminating debt rapidly is not a matter of luck or financial alchemy; it is the natural outcome of a deliberate, organized process. By systematically auditing your monthly spending, focusing surplus cash on the balances with the highest interest rates, negotiating lower borrowing terms, and ensuring all extra payments reduce the principal directly, you dismantle what you owe faster and at a much lower cost.
When the final debt payment is cleared, the disciplined habits you built during repayment become your most powerful financial asset. The income that once went to monthly interest charges and credit card bills remains entirely in your hands. You can then redirect that cash flow toward building an emergency reserve, investing for long-term growth, and funding major life milestones with total confidence.




