The Impact of AI and ML on the Finance Industry

What was once considered a niche piece of technology primarily associated with video games and experimental research has transformed into an essential pillar of everyday life. Today, artificial intelligence (AI) and machine learning (ML) extend far beyond online customer service chatbots and voice-activated digital assistants, establishing a powerful, permanent foothold across the modern finance industry.
From predicting market trends across global equity exchanges to actively identifying transactional fraud before unauthorized payments clear, machine learning systems are altering how institutions and households manage capital. The sheer speed, analytical precision, and data processing capabilities of modern algorithms allow institutional enterprises and retail consumers alike to rethink how money is tracked, invested, protected, and evaluated.
Key takeaways
- Machine learning replaces labor-intensive manual bookkeeping and emotional investing with disciplined, high-speed data analysis.
- Real-time automated fraud detection monitors millions of live transactions every second to flag suspicious activity before major losses occur.
- Algorithmic credit underwriting evaluates consumer debt-to-income metrics in seconds, eliminating subjective branch-level loan approvals.
- Computational accounting software minimizes routine human math errors, freeing finance professionals to focus on compliance and strategic audits.
- Algorithmic tools do not guarantee immunity from market risk and require active human oversight to interpret edge cases and maintain accuracy.
The evolution from manual calculations to automated workflows
For decades, the global financial system relied heavily on manual labor, paper trails, and interpersonal trust. Ledger sheets were balanced by hand, institutional account reconciliations required days of physical reviews, and loan eligibility often hinged on subjective evaluations by localized branch managers. When fundamental computer systems were introduced in commercial banking, they automated basic arithmetic, but the complex task of interpreting financial figures remained solely in human hands.
In equity markets, traditional investing required seasoned analysts to spend months or years studying company reports, reading annual balance sheets, and charting price patterns to project long-term returns. Other market participants operated purely on emotional impulses, speculation, or personal hunches. While human intuition occasionally resulted in lucrative returns, relying on emotional decision-making carried high degrees of volatility and risk. Furthermore, average retail investors seeking sound financial guidance were routinely priced out by the high advisory fees charged by wealth management firms.
Household budgeting followed a similarly labor-intensive path. Families recorded daily purchases line by line in physical notebooks, saving paper receipts in shoeboxes to balance their bank accounts at the end of each month. Loan departments evaluated paper paystubs, tax forms, and property deeds in branch offices without the benefit of centralized, algorithmic risk scoring models. As the volume of digital transactions surged and physical cash usage diminished worldwide, manually reviewing every ledger line became mathematically impossible.
The primary role of machine intelligence in finance is not to entirely replace human judgment, but to shoulder massive computational burdens, eliminate routine math errors, and surface critical anomalies.
Machine learning emerged as an essential evolutionary bridge, providing financial institutions with automated, data-driven processing systems capable of managing unprecedented scale. Rather than relying on rigid rules, machine learning engines adapt to incoming information streams, discovering hidden correlations across billions of data points that human reviewers could never process unaided.
Five key application areas reshaping modern finance
To grasp the scale of this operational transition, it is helpful to explore the core areas where automated systems and predictive algorithms have replaced traditional paper-based methods across institutions and households.
Predictive equity trading and market analysis
Unlike human analysts who require days to parse through company performance metrics and broader economic news, machine learning programs ingest multi-year trading histories and market movements in fractions of a second. By evaluating recurring chart patterns, trading volumes, and historical market cycles, these analytical models help project which equities are poised to trend upward and which ones risk falling over specific time horizons.
This systematic pattern recognition introduces calculated, disciplined strategies to market evaluation, replacing emotional guesswork. Furthermore, these algorithmic tools democratize market intelligence, giving everyday retail investors access to institutional-level analytical platforms without requiring thousands of dollars in professional consulting fees.
Automated fraud detection and security monitoring
Modern banking platforms process millions of credit, debit, and digital transactions every second. For human analysts, locating an unauthorized or fraudulent charge buried among thousands of normal transactions is mathematically impossible in real time. Machine learning algorithms continuously review live transaction streams, constructing baseline profiles of regular account behavior based on transaction size, location, and merchant history.
When an anomalous charge emerges—such as an unusual international purchase or an atypical charge volume—the system flags or blocks the transaction immediately. Rather than replacing human compliance teams, these automated shields highlight high-risk anomalies so security specialists can step in and conduct deeper investigations before substantial losses occur.
Algorithmic credit underwriting and risk evaluation
Evaluating loan applications once took weeks of manual file examination and subjective judgment. Today, algorithmic underwriting systems process incoming consumer data against predetermined risk criteria in real time. Rather than relying on static paper paystubs or personal meetings, automated credit models review diverse data points, including verified debt-to-income ratios, payment track records, and overall liability trends.
Within seconds, the software generates an approval decision alongside tailored interest rates and loan parameters. Because machine learning engines operate without personal sentiment, unconscious bias, or emotional sympathy, they produce calculated, objective determinations focused purely on risk modeling.
Corporate bookkeeping and algorithmic accounting
Routine bookkeeping has long been vulnerable to basic human error. Transposed digits, overlooked line items, and misplaced ledger entries routinely create compounding reconciliation problems for accounting teams. Automated accounting software systematically eliminates standard math errors by automating invoice reconciliation, general ledger postings, and balance sheet updates.
From small companies operating with ten employees to large enterprises within the Fortune 500, computational workflows reduce mundane mathematical errors down to near zero. This automation frees professional accountants from repetitive entry work, allowing them to focus on regulatory compliance, internal financial audits, and strategic capital allocation.
Personal expense tracking and digital budgeting
Household finance has shifted away from the shoebox-and-receipt model toward intelligent, automated oversight. Modern digital banking platforms incorporate native machine learning algorithms that instantly categorize daily card expenditures into specific categories, such as groceries, utilities, transportation, and discretionary spending.
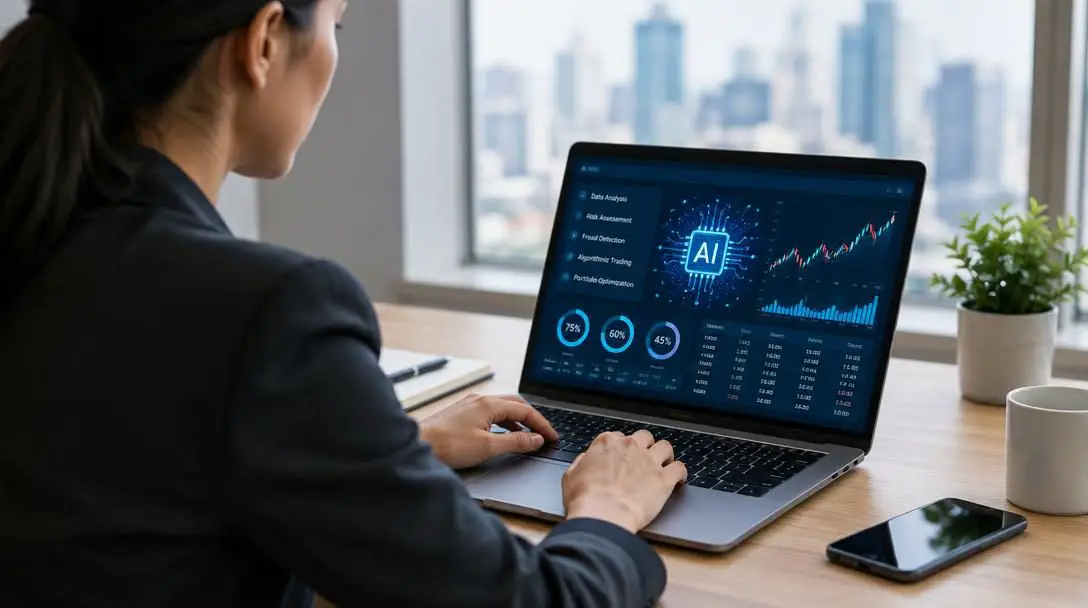
Instead of forcing consumers to log each expense manually, these tools track cash flow continuously, offering real-time balance views and spending notifications. By identifying recurring subscriptions and visualizing spending patterns, automated personal finance tools empower individuals to spot wasteful habits and manage their monthly budgets with minimal manual effort.
Comparing traditional finance methods to machine learning systems
The operational shift across global finance can be clearly contrasted when examining how traditional processes compare to modern algorithmic capabilities across critical functions.
| Operational area | Traditional method | Machine learning approach | Primary benefit |
|---|---|---|---|
| Equity market research | Manual reviews of quarterly filings and emotional speculation | Real-time ingestion of historical chart cycles and volume trends | Calculated pattern analysis without emotional guesswork |
| Fraud prevention | Manual reviews after customer reports unauthorized charges | Instant transaction stream analysis against account baselines | Immediate blocking of suspicious charges before settlement |
| Credit underwriting | Paper file audits and subjective branch manager meetings | Automated evaluation of live debt-to-income and payment data | Real-time objective approvals and risk-based interest rates |
| General bookkeeping | Manual ledger entry and physical invoice reconciliation | Automated ledger postings and digital bank feed syncing | Near-total elimination of standard mathematical errors |
| Household budgeting | Paper receipts saved in boxes and handwritten expense logs | Algorithmic categorization of card transactions and subscriptions | Continuous visibility into cash flow and spending leaks |
By moving from reactive post-mortems to proactive, continuous analysis, machine learning changes the baseline performance of modern financial operations. Where older workflows required days or weeks to uncover discrepancies, modern algorithms surface outliers within milliseconds.
Practical implementation steps for consumers and small businesses
Adopting financial automation does not require a deep technical background. Everyday consumers and small business operators can leverage these intelligent systems through straightforward, practical habits:
- Activate built-in banking budgeting tools: Turn on the automated spending categorization features already available within your mobile or desktop banking platform to track daily outflow without manual data entry.
- Set up automated recurring expense tracking: Configure your digital financial portal to map regular monthly bills, track upcoming due dates, and monitor recurring software or subscription costs.
- Turn on real-time security and fraud alerts: Permit your financial institutions to push instant text or application notifications whenever an unfamiliar transaction or out-of-pattern charge is identified.
- Use data-driven market research platforms: When studying market opportunities, use platforms that aggregate historical cycle trends and price metrics to make calculated decisions rather than relying on emotional impulses.
- Keep digital credit and income profiles current: Since automated underwriting tools assess live debt-to-income ratios, verify that all outstanding debts, credit limits, and income streams are accurately recorded before applying for digital credit products.
- Integrate automated accounting platforms: If operating a commercial venture, deploy accounting software that automatically syncs bank feeds, verifies arithmetic, and reconciles balances to prevent manual entry discrepancies.
Critical mistakes to avoid with financial algorithms
While algorithmic tools dramatically improve financial efficiency, over-reliance or misunderstanding can expose users to unnecessary operational and financial vulnerabilities. Keep the following pitfalls in mind when using automated financial software:
- Assuming algorithms eliminate all market risk: Predictive machine learning models identify mathematical probabilities based on historical data, but markets can shift unpredictably due to external events. Computational systems never guarantee immunity from market losses.
- Operating accounting software without human review: Even though automated tools reduce routine math errors to near zero, professional human oversight is still necessary to identify unique edge cases, adjust system parameters, and prevent bad input data from creating recurring balance sheet discrepancies.
- Ignoring security warnings and fraud notifications: Dismissing automated security alerts as false alarms without reviewing banking statements can allow bad actors to siphon capital unchecked.
- Neglecting underlying debt ratios before loan applications: Because automated underwriting systems render decisions strictly based on mathematical parameters like debt-to-income ratios, applying for automated credit without first addressing unresolved balances often results in instant, programmatic loan denials.
- Failing to audit categorized spending reports: Relying on budgeting algorithms without reviewing monthly summaries can cause mislabeled purchases to distort your actual expense tracking, masking areas where you could cut costs.
Frequently asked questions
Does machine learning eliminate all risk when trading in equity markets?
No. While machine learning programs process vast historical data sets, cycles, and volume patterns to identify mathematical probabilities, they cannot predict unexpected global events or eliminate market risk. Computational models provide disciplined analysis rather than guaranteed financial returns.
How do automated fraud detection systems identify unauthorized charges?
Automated security systems construct a baseline profile of an account's normal activity based on purchase size, geographic location, and merchant history. When an anomalous transaction occurs outside of these established parameters, the software flags or blocks it in real time for further review.
Can automated accounting tools replace professional human accountants?
No. Automated accounting systems eliminate routine data entry, balance sheet updates, and arithmetic errors, but professional human accountants remain essential for reviewing edge cases, ensuring strict regulatory compliance, and guiding strategic capital decisions.
Why do algorithmic underwriting systems reject some loans instantly?
Algorithmic underwriting tools make rapid lending decisions based strictly on hard data, such as debt-to-income ratios, credit history, and liability profiles. If an applicant's numbers do not meet the predetermined criteria, the system triggers an immediate programmatic decline without subjective human intervention.
How does automated expense tracking help households reduce spending leaks?
Automated budgeting tools continuously pull transaction data from bank feeds, sorting each card swipe into categories such as dining, subscriptions, and utilities. By displaying clear visualizations of monthly outflow, these platforms expose recurring subscription charges and unnoticed spending spikes that might otherwise go undetected.
The bottom line
The rise of artificial intelligence and machine learning represents a fundamental transformation in how modern financial systems operate. By replacing manual paperwork, subjective judgments, and error-prone accounting with rapid computational analysis, these technologies provide unprecedented accuracy and security across banking, underwriting, and investing.
However, technology remains an enhancer of financial intelligence rather than an absolute replacement for human responsibility. Whether tracking personal subscriptions, safeguarding an enterprise balance sheet, or navigating the volatility of public markets, achieving the best outcomes requires combining computational speed with disciplined oversight and informed personal judgment.