Understanding Mutual Funds and Index Funds
Entering the financial markets can be an overwhelming experience for newcomers facing thousands of individual stocks, corporate and government bonds, and complex trading terminology. Attempting to build an investment portfolio from scratch by purchasing single equities requires considerable research, ongoing monitoring, and enough starting capital to achieve adequate diversification across economic sectors.
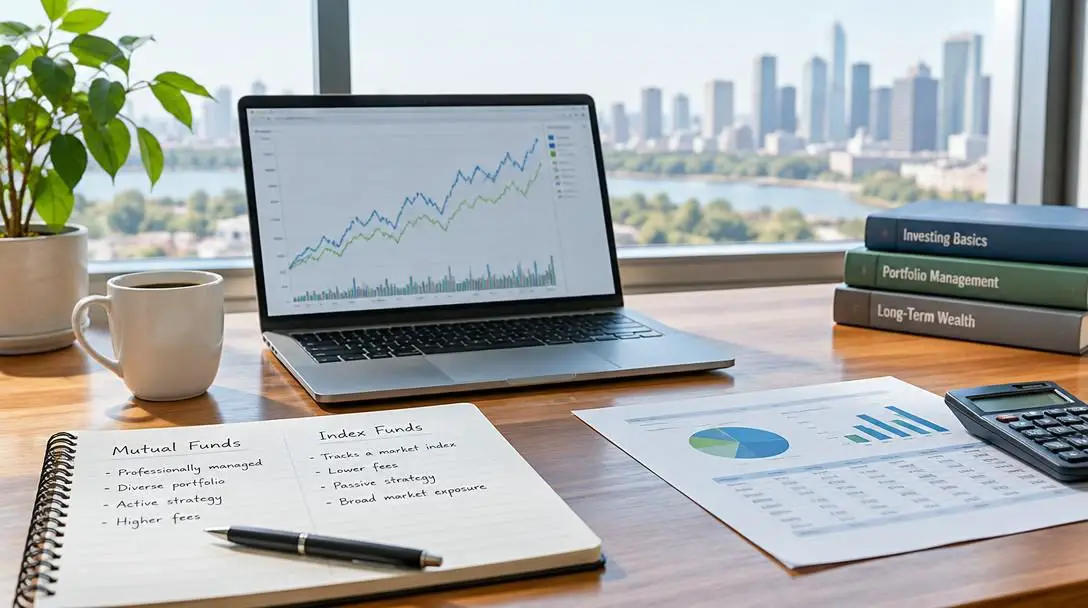
To solve this challenge, pooled investment vehicles bring together money from numerous participants to purchase large baskets of securities. Mutual funds and index funds represent the two most common collective investment vehicles available today, and while they share foundational mechanics, their underlying philosophies, management expenses, and performance expectations differ substantially.
Key takeaways
- An index fund is technically a specific, passively managed subset of mutual funds designed to mirror a benchmark.
- Actively managed mutual funds rely on professional portfolio managers who attempt to outperform the market through dedicated research and timely trading.
- Index funds offer lower expense ratios, greater simplicity, and improved tax efficiency because they trade securities far less frequently.
- Higher management fees and sales commissions can significantly erode net portfolio growth over multi-year investment horizons.
- Selecting the appropriate vehicle depends on individual financial objectives, personal risk tolerance, and whether an investor prioritizes low costs or potential market outperformance.
Understanding Pooled Investments: Mutual Funds and Index Funds
At their core, pooled investment structures allow participants to combine their capital into a unified buying pool. When you contribute money to a fund, you receive shares of that fund rather than owning the underlying securities directly. Each fund share provides an indirect ownership interest in every single stock, bond, or short-term security held within the aggregate portfolio.
What Is a Mutual Fund?
A mutual fund is an investment company that collects capital from thousands of retail and institutional investors to acquire a broad portfolio of assets, most commonly stocks or bonds. Professional fund managers oversee these portfolios and execute trades in alignment with a defined investment objective, such as long-term capital appreciation, consistent income generation, or capital preservation.
Mutual funds fall into two broad structural philosophies: active management and passive management. In an actively managed fund, a lead manager or an investment committee conducts in-depth economic analysis, evaluates corporate balance sheets, and buys or sells assets based on their judgment. In contrast, a passively managed mutual fund foregoes individual security selection entirely, choosing instead to replicate the holdings of an established market benchmark.
What Is an Index Fund?
An index fund is a specialized mutual fund that tracks a designated financial market index, such as the S&P 500 or the Dow Jones Industrial Average. Unlike actively managed vehicles, index funds operate under strict passive rules: they purchase the exact assets contained within the benchmark in identical proportions, making no subjective bets on whether specific companies will rise or fall.
Because index funds follow this mechanical approach, they eliminate the need for forecasting market swings or timing market entry. Investors use them as an efficient mechanism for securing instant, transparent exposure to entire market sectors or the broader economy as measured by the tracked index.
Comparing Core Fund Strategies
Understanding how active and passive vehicles differ in practice helps clarify where each fits within an overarching financial plan. The table below outlines key operational differences across actively managed funds and two prominent index-tracking strategies.
| Fund Type | Management Approach | Primary Objective | Security Selection | Relative Cost Structure |
|---|---|---|---|---|
| Actively Managed Mutual Fund | Active discretionary oversight | Outperform a benchmark or target goal | Research-driven selection by fund manager | Higher fees and sales commissions |
| S&P 500 Index Fund | Strictly passive replication | Match performance of 500 large U.S. companies | Replicates designated index components | Low operational and management expenses |
| Dow Jones Industrial Average Index Fund | Strictly passive replication | Match performance of 30 blue-chip companies | Replicates designated index components | Low operational and management expenses |
The Mechanics and Dynamics of Mutual Funds
Mutual funds function by gathering vast sums of money to unlock economies of scale that individual savers cannot access on their own. Once cash enters the fund, the portfolio manager and their research staff screen thousands of prospective investments, review corporate earnings reports, track macroeconomic indicators, and adjust portfolio allocations to reflect current conditions.
Pooled investment vehicles allow everyday investors to harness broad economic growth without having to analyze dozens of corporate balance sheets independently.
Advantages of Investing in Mutual Funds
- Instant Diversification: Purchasing shares in a single mutual fund instantly spreads an investor's capital across dozens or hundreds of different companies and sectors, cushioning the blow if an individual company falters.
- Full-Time Professional Oversight: Investors who lack the time, training, or interest to research individual balance sheets benefit from experienced financial professionals who monitor markets daily.
- Potential for Outperformance: Skilled managers who successfully identify undervalued securities or rotate into defensive sectors before a downturn can potentially deliver returns that exceed general market averages.
- Broad Market Accessibility: Mutual funds enable everyday investors to participate in diversified asset classes with modest initial contributions, bypassing the high capital requirements needed to buy individual shares across dozens of firms.
Disadvantages and Trade-Offs of Mutual Funds
- Substantially Higher Costs: Active management requires significant overhead, including research teams, analytical software, and administrative overhead. These expenses, along with potential sales commissions, translate into higher expense ratios that diminish cumulative gains over time.
- Zero Control Over Holdings: Individual shareholders have no say in which specific equities the fund buys, holds, or sells, leaving all portfolio composition decisions entirely to the manager's discretion.
- Vulnerability to Manager Risk: An active manager's timing mistakes, flawed economic forecasts, or poor stock picks can cause a mutual fund to experience pronounced volatility and underperform passive market benchmarks.
The Mechanics and Dynamics of Index Funds
Index funds discard the ambition of outsmarting the market in favor of replicating it with mathematical precision. When you invest in an index fund tracking a benchmark like the Dow Jones Industrial Average or the S&P 500, the fund allocates incoming capital across the constituent companies strictly according to the index methodology. Because the list of holdings is set by the benchmark provider, human bias and subjective forecasts play no role in portfolio construction.
Advantages of Investing in Index Funds
- Ultra-Low Operating Expenses: Because index funds do not maintain costly analytical teams or execute frequent discretionary trades, their management fees and operational costs remain exceptionally low compared to actively managed peers.
- Superior Tax Efficiency: Passive tracking requires minimal portfolio turnover. By trading far less frequently than active managers, index funds realize fewer capital gains, which reduces taxable capital gains distributions for investors holding shares in taxable brokerage accounts.
- Operational Simplicity and Transparency: Because holdings are dictated by public indexes, shareholders always know exactly what companies they own without having to wait for quarterly portfolio disclosure updates.
Disadvantages and Limitations of Index Funds
- No Downside Mitigation: Because index funds are bound to their benchmark, they cannot sell struggling constituents, raise cash reserves, or rotate into defensive assets during a market downturn.
- Capped Upside Potential: An index fund is designed strictly to match the market, meaning it will never beat the benchmark it tracks; investors give up the possibility of capturing outsized alpha returns.
- Potential Concentration Risks: Certain benchmarks are heavily weighted toward specific megacap companies or specific market sectors, meaning an index tracker might be less diversified than an active fund that intentionally balances its exposure.
Step-by-Step Guide: How to Choose the Right Fund Vehicle
Determining whether to place your capital in an actively managed mutual fund or a passive index fund requires an objective assessment of your financial roadmap, risk appetite, and fee sensitivity. Follow this structured process to evaluate your options:
- Define Your Investment Objective: Determine the explicit goal of the capital you plan to invest. Decide whether your priority is aggressive long-term capital appreciation, reliable income generation through dividend-paying assets, or capital preservation. Establish whether your timeline requires matching market returns or attempting to beat them through active oversight.
- Assess Your Personal Risk Tolerance: Gauge your emotional and financial capacity to withstand market turbulence. If fluctuations stemming from a specific fund manager's active stock selection keep you awake at night, passive market tracking provides a smoother psychological ride. If you tolerate volatility in pursuit of potential excess returns, an active fund may fit your profile.
- Scrutinize the Complete Fee Schedule: Examine the fund's expense ratio, which reflects the annual percentage of assets deducted for administrative and management expenses. Check for front-end or back-end sales commissions, trading costs, and 12b-1 marketing fees, calculating how those deductions will affect your net compound returns over 10, 20, or 30 years.
- Examine Underlying Portfolio Diversification: Look closely at the actual securities inside each fund under consideration. Determine whether a benchmark like the S&P 500 or the Dow Jones Industrial Average offers the sector balance you desire, or whether an actively managed fund provides a broader, more tailored assortment of equities and bonds across domestic and international markets.
- Evaluate the Investment Strategy and Mandate: For an active mutual fund, review the lead manager's tenure, investment philosophy, and historical consistency through varying market cycles. For an index fund, verify the benchmark tracked to ensure the underlying index matches the exact asset class or industry exposure you intend to target.
Pitfalls to Avoid When Building Your Portfolio
Navigating the fund universe requires vigilance, as subtle structural misunderstandings can derail an otherwise sound wealth-building strategy. Keep the following common errors in mind:
- Overlooking the Impact of Fees: Failing to account for management fees and sales commissions is a frequent error. Even small percentage fee differences accumulate over years, siphoning away significant portions of investment growth.
- Assuming All Mutual Funds Are Actively Managed: Many investors treat mutual funds and index funds as mutually exclusive categories. In reality, index funds are simply a passive variety of mutual funds; mutual funds can be either active or passive.
- Expecting Index Funds to Beat the Market: Index funds are engineered to copy a benchmark, not surpass it. Expecting an index tracker to navigate around declining companies or generate excess returns during volatile market cycles reflects a basic misunderstanding of passive investing.
- Assuming Active Management Guarantees Safety: Hiring a professional manager does not eliminate market risk. Discretionary decisions, ill-timed security sales, or concentrated bets can lead to severe drawdowns that exceed broad market declines.
- Ignoring Tax Drag: Disregarding the tax consequences of active trading can lead to unexpected tax liabilities. Actively managed funds that trade frequently distribute realized capital gains to shareholders, creating annual tax events that index fund holders largely avoid.
Frequently asked questions
Can a fund be both a mutual fund and an index fund?
Yes. An index fund is a specific type of mutual fund. While standard mutual funds can be managed actively by human analysts, an index mutual fund is structured to passively track a designated market benchmark like the S&P 500.
Why do actively managed mutual funds charge higher fees?
Actively managed mutual funds carry higher expense ratios because they employ professional fund managers and analysts who conduct intensive research, evaluate corporate balance sheets, and execute frequent trades. These operational costs, along with marketing expenses and potential sales commissions, are passed on to fund shareholders.
Do index funds protect investors during a market crash?
No. Index funds are bound to their benchmark and cannot sell off declining companies, buy defensive hedges, or hold significant cash reserves. If the tracked market index falls by thirty percent, the index fund will fall by roughly that exact same amount.
How do index funds achieve superior tax efficiency?
Index funds generate fewer taxable events because they only buy or sell shares when the composition of the tracked index changes or when accommodating shareholder inflows and outflows. By keeping portfolio turnover low, they distribute fewer capital gains to investors than actively traded funds.
Which option is better for a complete beginner?
For most beginners seeking straightforward, low-cost diversification, broad index funds provide a transparent foundation that eliminates the risk of poor manager selection and minimizes drag from high annual fees.
The bottom line
The choice between actively managed mutual funds and passive index funds ultimately rests on your individual objectives, risk tolerance, and views on market efficiency. Active mutual funds offer the specialized insights of professional managers who seek to outperform standard benchmarks, which may appeal to investors comfortable paying higher management expenses in pursuit of potential market-beating returns.
Conversely, index funds deliver an ultra-low-cost, tax-efficient, and transparent way to capture broad market gains through passive replication of trusted benchmarks like the S&P 500 and the Dow Jones Industrial Average. Before deploying your hard-earned capital, review your existing investments, examine the total fees you currently pay, and select the vehicle that best advances your long-term financial security.