5 Tips To Becoming An Effective Investor
Investing serves as one of the most reliable vehicles for building long-term wealth, yet entering financial markets without a defined framework often leads to frustration. Many newcomers approach investing with expectations of rapid profits, only to discover that market prices fluctuate constantly in response to economic cycles, corporate earnings reports, geopolitical events, and shifting consumer behavior. Achieving financial independence through investing rarely happens overnight; it demands consistent habits, objective evaluation, and emotional poise.
To navigate market volatility successfully, you must look past everyday speculation and establish an evidence-based roadmap. Becoming an effective investor is not about timing market peaks or bottoms, but rather about positioning capital so it can compound steadily over decades while weathering inevitable downturns. By mastering the core fundamentals of risk, diversification, and asset allocation, you can shift from simply saving wages to putting your resources to work efficiently.
Key takeaways
- Thorough research into financial statements, leadership teams, and industry trends helps eliminate guesswork from investment decisions.
- Diversifying across stocks, bonds, real estate, and other asset classes shields your overall portfolio from single-asset failures.
- Maintaining a long-term perspective prevents reactive trading driven by sensationalized financial headlines.
- Emotional discipline protects capital by curbing the natural impulses of fear during downturns and greed during rallies.
- Working with qualified financial professionals provides objective guidance and structural planning tailored to your personal goals.
Understanding the reality of risk and reward
Every investment decision involves an inherent balance between risk and potential reward. In financial markets, no asset is guaranteed to produce profits, and past performance provides no assurance of future returns. Recognizing this fundamental relationship allows you to evaluate opportunities realistically rather than chasing unrealistic expectations. Market valuations rise and fall based on broader macroeconomic shifts, corporate performance, and geopolitical conditions, meaning risk cannot be eliminated entirely.
Instead of attempting to eliminate risk, skilled investors focus on risk management. Accepting that economic contractions and market declines are normal elements of the financial landscape enables you to design a resilient portfolio. By structuring your holdings to withstand market pullbacks, you ensure that temporary price drops do not undermine your broader financial security.
The five essential pillars of effective investing
Building an enduring investment portfolio requires adopting core habits that guide your decision-making across all market environments. These five foundational principles provide the structure needed to navigate changing economic conditions with confidence.
Do your research
Committing capital without proper verification exposes you to avoidable losses. Performing thorough due diligence ensures that you understand the underlying business model, the forces driving revenue, and the external threats facing an enterprise. Making investment choices based on online chatter or casual recommendations frequently results in owning businesses whose operational realities you do not understand.
Comprehensive investment research involves several distinct evaluative components:
- Analyzing company financials: Scrutinize audited balance sheets, income statements, and cash flow records to assess revenue expansion, debt obligations, profit margins, and cash reserves.
- Evaluating the management team: Review executive leadership, examining their track record, governance history, and capital allocation strategies.
- Assessing industry trends: Determine whether the broader sector benefits from secular growth, faces regulatory headwinds, or contends with technological disruption.
- Identifying potential risks: Examine internal vulnerabilities, competitive pressures, and supply chain dependencies that could hurt future profitability.
Diversify your portfolio
Diversification serves as a primary defense against unexpected capital loss. Spreading allocations across various companies, industries, and broad asset classes ensures that a sharp decline in one specific holding does not severely damage your entire portfolio. When your assets are appropriately uncorrelated, stable or advancing assets help offset those experiencing temporary declines.
A resilient asset allocation strategy typically balances multiple core categories:
- Stocks: Equities convey fractional ownership in operating companies, delivering higher long-term capital growth potential alongside higher short-term price volatility.
- Bonds: Fixed-income securities pay regular interest and historically experience lower volatility than stocks, providing balance and income.
- Real estate: Physical property holdings provide exposure to physical assets, potential rental yields, and unique economic performance factors.
- Other assets: Alternative investments and non-correlated holdings introduce further variety, reducing dependence on standard market movements.
Have a long-term mindset
Successful wealth creation requires patience and the willingness to let multi-year business cycles play out. Financial markets experience constant fluctuations driven by short-term trading liquidity, macroeconomic data releases, and media narratives. Attempting to profit from every short-term wiggle often causes investors to trade excessively, buying during moments of peak euphoria and selling in panic during downturns.
Adopting a long-term view allows you to focus on corporate earnings growth and broader economic productivity rather than daily price fluctuations. Filtering out daily market commentary keeps your focus aligned with personal goals like retirement or generational wealth building, making temporary turbulence far easier to endure.
The investors who achieve lasting results are typically those who remain committed to their frameworks regardless of prevailing market sentiment.
Stay disciplined
Developing an investment plan is straightforward, but maintaining execution during volatile market environments demands strict emotional control. Market downturns naturally trigger fear, tempting investors to sell off sound assets to prevent further paper declines. Conversely, rapid bull markets stoke fear of missing out, tempting individuals to chase overpriced, speculative holdings.
Achieving consistent outcomes requires viewing investing as an extended marathon rather than a short sprint. By predetermining how you will respond to market declines, you remove damaging emotional impulses from your routine. Disciplined consistency ensures you remain invested through downswings, positioning your portfolio to capture the full benefit of subsequent market recoveries.
Seek professional advice
Navigating modern financial markets requires time, technical comprehension, and continuous administrative attention. If managing asset allocation models, tax considerations, and long-term rebalancing feels overwhelming, collaborating with an experienced financial advisor or investment manager can provide substantial value.
A qualified financial professional delivers an objective, outside perspective, helping you develop an individualized roadmap aligned with your specific risk capacity and timeline. During periods of severe market turbulence, an advisor acts as a behavioral guardrail, preventing emotional liquidations and keeping your wealth accumulation strategy on track.
Comparing core investment asset classes
Effective portfolio construction depends on matching specific asset types with your financial objectives, time horizon, and risk tolerance. The following table highlights the characteristics of the primary asset classes used to build a balanced portfolio.
| Asset Class | Primary Objective | Risk Level | Expected Volatility | Income Potential |
|---|---|---|---|---|
| Stocks | Long-term capital growth | Moderate to High | High | Variable (Dividends) |
| Bonds | Capital preservation & stability | Low to Moderate | Low to Moderate | Fixed (Interest yields) |
| Real Estate | Income & inflation hedging | Moderate | Moderate | Steady (Rental yields) |
| Cash Equivalents | Liquidity & emergency reserves | Very Low | Minimal | Modest (Short-term yield) |
Proven strategies for mitigating portfolio risk
Beyond baseline diversification, seasoned investors integrate structural risk-management tools to protect their capital against severe downturns. Implementing these techniques allows you to pursue growth without exposing your assets to existential losses.
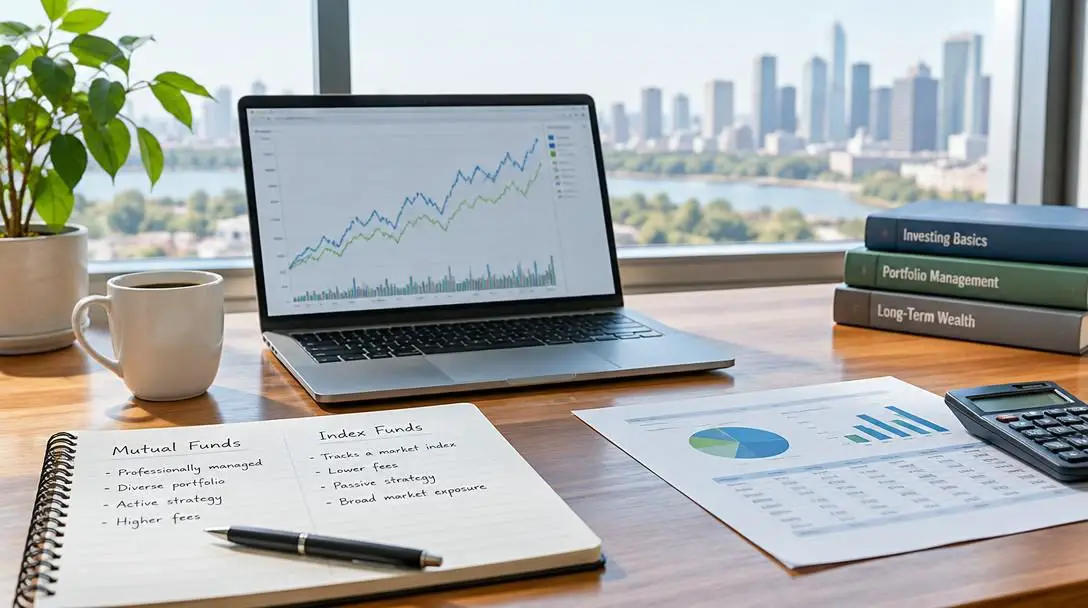
One accessible way to lower portfolio risk is utilizing low-cost index funds or exchange-traded funds (ETFs). Rather than attempting to select single winning stocks, index funds track established market benchmarks such as the S&P 500. This approach provides instant exposure to hundreds of large-cap enterprises in a single vehicle, removing single-company risk at minimal expense.
When selecting individual corporate holdings, focusing on foundational business strength provides additional defensive stability. Companies featuring robust competitive fundamentals are much better equipped to handle economic recessions. Prioritize businesses that exhibit:
- A solid balance sheet: Modest debt obligations and healthy cash reserves that insulate the enterprise when credit markets tighten.
- Predictable free cash flow: Reliable operational earnings that fund research, settle liabilities, and support dividend distributions.
- A clear competitive advantage: Distinct structural moats—such as proprietary technology, cost advantages, or high switching costs—that defend market share against competitors.
How the wealth-building process works
To stay committed to an investment plan, it helps to understand the underlying mechanics of market appreciation. Investing is fundamentally different from speculation because it relies on the ownership of productive economic assets. When you acquire shares in an enterprise, you participate directly in the revenue, technological innovations, and cash distributions produced by that business. When you hold debt securities, you receive contracted interest payments backed by corporate or governmental issuers.
Over extended holding periods, productive enterprises expand their earnings capabilities, adapt to consumer preferences, and enhance productivity. Furthermore, compound growth exponentially expands your wealth over decades. When investment distributions, dividends, and interest payments are systematically reinvested, they generate their own earnings. Interrupting this compounding engine through frequent, emotional trades drastically curtails its long-term power.
Step-by-step roadmap to start investing
Putting theoretical investing principles into practice requires an organized, repeatable implementation process. Following these steps helps build an enduring portfolio with minimal friction:
- Define your financial objectives: Identify your exact investment timeline and target goals, such as saving for retirement, buying a home, or generating passive income.
- Determine your asset allocation: Establish an asset split across stocks, fixed income, real estate, and cash reserves that reflects your personal risk tolerance.
- Select broad-market funds or core holdings: Focus your initial capital on low-cost, broadly diversified index funds, ETFs, or fundamentally sound individual companies with clear competitive advantages.
- Establish systematic research habits: Schedule periodic reviews of corporate balance sheets, sector developments, and expense ratios prior to committing new funds.
- Automate your contributions: Configure recurring monthly transfers into your investment accounts to enforce disciplined accumulation regardless of market conditions.
- Engage professional counsel when appropriate: Consult a qualified advisor to address complex tax implications, estate planning goals, or customized portfolio rebalancing.
Costly investment mistakes to avoid
Even motivated individuals often make behavioral and tactical errors that erode investment performance. Keeping these common missteps in mind helps you protect your capital and stay aligned with your long-term roadmap:
- Chasing recent high flyers: Purchasing an asset solely because its market price surged recently often means buying at overextended valuations right before an inevitable decline.
- Reacting emotionally to market headlines: Financial news focuses on dramatic, short-term developments designed to grab attention. Making sudden portfolio changes based on headlines disrupts long-term plans.
- Concentrating capital into a single asset: Placing an outsized percentage of your net worth in a single company or industry leaves your wealth vulnerable to unexpected corporate failures.
- Allowing fear and greed to govern trades: Liquidating assets during temporary pullbacks locks in paper losses, while greed leads to chasing unvetted, speculative trends.
- Ignoring administrative and fund fees: High fund management fees, advisory expenses, and transaction costs quietly deplete cumulative investment returns over decades.
Frequently asked questions
How much money do I need to start investing effectively?
Modern investment vehicles like exchange-traded funds and fractional-share trading enable you to start investing with very modest sums. The key is establishing a consistent contribution habit rather than waiting to amass a large initial lump sum.
What is the difference between investing and speculation?
Investing focuses on purchasing productive assets—such as businesses or bonds—that generate cash flows and economic value over multi-year periods. Speculation involves trading assets based on short-term price movements and market sentiment without regard to underlying fundamentals.
How often should I review and rebalance my portfolio?
Reviewing your portfolio once or twice a year is generally sufficient to ensure your target asset allocation remains balanced. Checking account values daily often triggers emotional stress and promotes counterproductive, impulsive trades.
Why are low-cost index funds recommended over individual stock picking?
Index funds instantly spread your investment across hundreds of companies, reducing single-firm risk while charging minimal management fees. This allows you to capture general economic expansion without having to evaluate and monitor individual balance sheets continuously.
When does it make sense to hire a professional financial advisor?
Engaging a financial advisor is especially beneficial when you manage substantial capital, face intricate tax or estate planning issues, or struggle to control emotional impulses during volatile market corrections.
The bottom line
Becoming an effective investor does not require complex trading systems or the ability to forecast market cycles. Lasting financial progress is built upon the consistent application of sound principles: conducting thorough research, diversifying across multiple asset categories, preserving a multi-year horizon, adhering to structural discipline, and seeking professional guidance when necessary. By grounding your investment approach in these core tenets, you can successfully manage risk, capture economic growth, and achieve your financial goals over time.