
Developing A Budget To Track Expenses And Maximize Savings: 5 Tips
Developing a budget is one of the most fundamental pillars of sound personal financial management. It acts as a clear blueprint for how you allocate your incoming resources, meet daily necessities, and set aside funds for future milestones. Despite being a universal necessity, establishing a financial management plan can feel daunting, particularly when trying to balance immediate lifestyle desires against future financial stability. Without intentional oversight, even minor discretionary expenditures can quietly accumulate over the course of a single month, leaving little to no capital available for savings.
When properly constructed, a personal budget is not a rigid or punitive exercise; rather, it is a supportive tool designed around your lifestyle, personal goals, and day-to-day spending patterns. Understanding precisely where your money originates and where it flows grants you the agency to direct your cash flow with clear purpose rather than constantly reacting to shortfalls as they occur. By aligning your regular expenses with your actual earnings, you can steadily maximize your savings and construct enduring financial security without sacrificing your essential well-being.
Key takeaways
- A realistic budget balances incoming cash flow against outgoing expenses while treating savings as an intentional monthly obligation.
- Separating non-negotiable living essentials from discretionary lifestyle desires ensures core needs are consistently covered first.
- Building an emergency reserve prevents routine disruptions, such as medical bills or vehicle repairs, from causing high-interest debt.
- Financial plans must evolve over time to accommodate income shifts, lifestyle changes, and broader economic factors like inflation.
Understanding Budget Mechanics and Cash Flow Dynamics
At its foundation, a personal budget functions as an operational mechanism to compare total incoming funds against total outgoing obligations. The overarching objective is to balance these two streams so that expenditures never surpass total income, while methodically reserving a portion of your revenue for an emergency cushion and long-term financial milestones. When incoming revenue is greater than outgoing spending, you generate a net cash flow surplus, which can be deployed toward wealth-building. Conversely, spending more than you earn creates a budget deficit, highlighting the urgent need to modify consumption habits.
To effectively manage this flow, expenditures must be divided into distinct categories based on their recurrence, necessity, and degree of flexibility. Categorizing costs provides immediate transparency into your spending habits and reveals which outlays can be trimmed when financial pressures arise.
| Expense Category | Operational Definition | Primary Examples | Spending Flexibility |
|---|---|---|---|
| Fixed Essential | Non-negotiable obligations that recur at predictable intervals and consistent amounts. | Rent or mortgage payments, basic utility bills | Rigid; mandatory for maintaining shelter and basic living standards. |
| Variable Essential | Necessary baseline costs that fluctuate in total dollar amount from month to month. | Standard household groceries, basic transportation | Moderate; quantities can be adjusted, but baseline consumption is mandatory. |
| Discretionary | Elective lifestyle, leisure, and entertainment preferences. | Dining out at restaurants, cinema visits, personal hobbies | High; can be paused or substantially reduced without impacting survival. |
| Periodic or Irregular | Infrequent, unpredictable, or episodic financial demands that arise intermittently. | Automotive servicing, urgent medical bills, home maintenance | Low predictability; requires an established cash buffer to handle. |
A well-designed budget transforms financial management from a restrictive chore into a supportive tool for long-term independence.
5 Core Tips for Developing an Effective Budget
Creating a budget that is both sustainable and capable of maximizing long-term savings requires a structured methodology. Applying these core practices ensures that your spending framework remains grounded in reality while actively protecting your future financial stability.
1. Be Realistic About Your Income and Expenses
A reliable budget cannot be constructed on wishful thinking, rough estimations, or best-case scenarios. It requires total honesty regarding both what you earn and what you spend every single day. When tallying your incoming funds, focus strictly on guaranteed, realized earnings. Variable items such as potential employment bonuses, prospective overtime, or expected monetary gifts should never be counted as baseline income until the funds have officially cleared into your account.
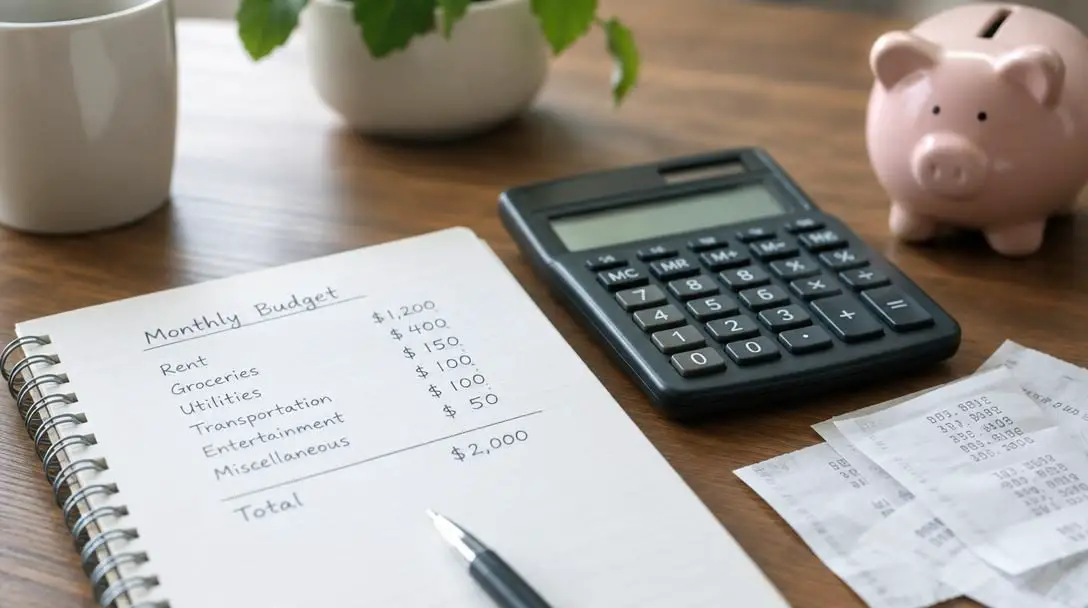
On the expenditure side, accurate tracking requires accounting for every single dollar that leaves your hands. Minor, habitual purchases—such as daily convenience items, impulse purchases, or forgotten recurring digital subscriptions—can quickly drain your accounts if they go unmonitored. Leveraging dedicated tracking mechanisms, such as manual spreadsheets, online budgeting software, or mobile financial applications, ensures that every single transaction is captured and accounted for.
2. Prioritize Your Spending
Once your complete transaction history is visible, the next essential phase is prioritizing where your money goes. This requires drawing a firm boundary between absolute necessities and discretionary choices. Essential obligations include non-negotiable living costs that keep your household operational: shelter expenses like rent or mortgages, fundamental utility bills, and basic groceries required to sustain your family's health.
Discretionary spending, by contrast, includes elective lifestyle choices such as dining out at restaurants, attending the cinema, or funding personal hobbies. While these activities offer recreation and personal fulfillment, they are optional for survival. Ensuring that essential obligations and savings contributions are funded first reveals precisely what residual capital remains for discretionary enjoyment, keeping you from overspending on non-essentials at the expense of your core obligations.
3. Plan for Unexpected Expenses
A financial framework that only accounts for predictable, recurring monthly bills remains constantly vulnerable to external shocks. Real life frequently introduces unexpected costs, such as sudden automotive breakdowns, urgent medical emergencies, or necessary home repairs. Without an advance plan to absorb these events, an unexpected invoice can instantly derail your monthly cash flow and erase recent progress.
To insulate your household from financial distress, designate a specific sum of money each month solely for an emergency reserve fund. Consistently contributing to an emergency account creates a reliable buffer that absorbs life's surprises. Having dedicated liquid cash available allows you to handle critical vehicle repairs or healthcare needs without depleting your primary savings accounts or relying on high-interest credit cards to get by.
4. Revisit and Adjust Your Budget Regularly
A personal budget is an evolving framework rather than a static document that is filed away after a single draft. As personal circumstances and broader economic conditions shift, your financial plan must adapt to maintain its real-world relevance. Earning adjustments, such as receiving a workplace promotion or experiencing an income drop due to reduced hours, necessitate an immediate recalibration of your spending and savings allocations.
External market factors also exert pressure on household finances. Broader economic shifts, particularly inflation and the rising cost of everyday goods, naturally increase what you must spend on basic essentials like groceries and energy services. Periodically reviewing and updating your budget figures ensures that your financial roadmap remains an accurate reflection of your ongoing lifestyle, resource levels, and future aspirations.
5. Consider Enlisting Professional Help
Managing personal finances and designing a balanced cash-flow system can become overwhelming, especially when facing complicated income structures, substantial debt, or major life transitions. When self-directed spreadsheets and budgeting applications feel insufficient to tackle your financial goals, seeking external expertise can provide the necessary direction.
Working alongside a qualified professional, such as a certified credit counselor or an accredited financial advisor, offers personalized guidance tailored to your specific situation. These specialists provide an objective view of your cash management habits, help pinpoint ongoing spending inefficiencies, and assist in designing a balanced budget structured around your economic reality. Their expertise empowers you to make informed decisions that promote long-term financial health.
Practical Steps to Set Up Your Budget
Translating budgeting theory into an operational routine is straightforward when broken down into sequential actions. Following a methodical process ensures that your financial framework remains organized and resilient from the start.
- Gather Your Financial Documentation: Collect recent pay stubs, bank statements, utility invoices, credit card statements, and receipts from cash outlays over the past few months. Having comprehensive records on hand ensures that no recurring costs or irregular transactions are overlooked.
- Determine Your Actual Monthly Income: Calculate the accurate, take-home pay you receive every month after taxes and deductions. If your earnings fluctuate due to freelance or hourly work, adopt a conservative baseline rather than using your peak earning periods to avoid creating an unrealistic plan.
- Itemize Every Monthly Expense: Review your financial statements and write down every single expense incurred during a typical month. Use a dedicated spreadsheet, an online application, or specialized budgeting software to categorize and log these outlays systematically.
- Classify Essential versus Discretionary Outlays: Group all recorded costs into clear divisions. Label non-negotiable housing, basic nutrition, and essential utility services as necessities, while categorizing recreation, restaurant meals, and hobbies under discretionary lifestyle spending.
- Allocate Dedicated Savings and Emergency Money: Treat savings and emergency reserve funding as mandatory line items rather than afterthoughts. Direct a defined portion of your monthly income straight into an emergency reserve to build resilience against vehicle upkeep, household repairs, or medical needs.
- Calculate Your Balance and Refine: Subtract your total expenses and savings targets from your baseline take-home income. If the calculation yields a deficit or leaves no room for savings, systematically trim discretionary categories until your cash flow balances.
Common Budgeting Mistakes to Avoid
Even the most dedicated budgeting efforts can stumble if common financial missteps are not anticipated. Keeping your spending plan effective requires avoiding several pervasive mistakes:
- Omitting Minor Daily Outlays: Disregarding small convenience items, impulse treats, and minor recurring charges can silently erode your monthly surplus, leaving you short on cash despite overall careful planning.
- Relying on Optimistic Income Projections: Budgeting based on anticipated work bonuses, hypothetical overtime, or unpredictable monetary gifts creates a fragile plan that collapses if those funds fail to arrive.
- Failing to Fund an Emergency Reserve: Omitting an emergency fund leaves you completely unprotected against urgent vehicle repairs or sudden medical events, frequently driving households into expensive debt.
- Treating the Budget as Unchanging: Refusing to modify your figures when your income, family situation, or market costs shift due to inflation renders your budget obsolete and unworkable over time.
- Enforcing Overly Restrictive Spending Caps: Eradicating all recreational outlays leads quickly to financial burnout. A sustainable framework balances core obligations and savings goals with reasonable, intentional entertainment spending.
Long-Term Outlook: Moving Beyond Basic Budgeting
Once you have developed a functioning budget that balances your monthly cash flow and maintains an initial emergency buffer, you can turn your focus toward long-term wealth building. A consistent surplus provides the financial runway needed to address broader goals with confidence.
As your dedicated emergency reserve reaches a stable, self-sustaining balance, you can begin redirecting extra monthly cash flow toward other critical targets, such as eliminating high-interest debt, increasing contributions toward retirement accounts, or saving for major life assets. Continue maintaining regular oversight of your daily transactions through your preferred tracking platform. If your financial profile grows more complex through career advancements or expanding household needs, partnering with a financial advisor or credit counselor will ensure your wealth management plan adapts seamlessly to your changing life.
Frequently asked questions
How do I budget if my monthly income fluctuates?
When dealing with variable income, calculate your monthly baseline using your lowest-earning periods rather than an average or peak month. Construct your budget around this conservative base to guarantee that essential housing, food, and utilities are always covered. When higher-earning months occur, allocate the surplus directly toward your emergency reserve or dedicated savings rather than inflating your discretionary lifestyle spending.
What should I do if my budget calculations reveal a deficit?
If your combined expenses and savings targets exceed your monthly income, immediately examine your discretionary spending categories. Temporarily cut or reduce elective costs such as dining out, personal entertainment, and leisure subscriptions. If discretionary reductions are insufficient to resolve the deficit, investigate ways to reduce variable essentials or explore opportunities to increase your baseline income.
Why must an emergency fund be treated as an ongoing budget line item?
Treating emergency savings as an active monthly line item ensures that you consistently build a dedicated financial buffer before you spend on discretionary desires. Without an established cash reserve, common unexpected disruptions like automotive repairs, urgent home maintenance, or medical bills will force you to liquidate long-term savings or rely on high-interest credit cards.
How often should a personal budget be reviewed and adjusted?
A budget should be evaluated on a regular basis, ideally monthly for daily expense tracking and quarterly for broader balance reviews. In addition to scheduled reviews, update your budget whenever major life events take place, such as receiving a pay raise, undergoing an income reduction, moving to a new home, or navigating rising living costs due to broader economic inflation.
When should I consider enlisting a financial professional?
You should consider consulting a financial advisor or certified credit counselor if managing your budget feels overwhelming, if you have complex or irregular income streams, or if you are struggling with persistent debt hurdles. A qualified professional can provide an objective perspective, identify spending inefficiencies, and help you structure a balanced financial plan tailored to your specific circumstances.
The bottom line
Personal budgeting is not about depriving yourself of life's pleasures; it is about establishing intentional control over your economic resources. By realistically assessing what you earn, categorizing your expenses, and methodically funding both an emergency cushion and future goals, you protect your household against unexpected hardships while systematically growing your wealth. With patience, consistent tracking, and periodic adjustments, your budget becomes a powerful foundation for lifelong financial independence.




