The Basics of Investing: What Everyone Should Know
Investing stands as one of the most effective tools for building lasting wealth and securing long-term financial independence. While conventional savings accounts allow individuals to reserve cash for immediate emergencies, investing requires committing financial capital to assets with the expectation of generating an ongoing return or seeing that initial capital increase in value over time. Navigating this landscape, however, can feel intimidating for newcomers who encounter unfamiliar terminology, a dizzying array of products, and erratic market movements.
Fortunately, the foundational principles of finance are straightforward and logical once broken down into their core components. Learning how capital behaves across different economic environments, understanding the mechanics that drive asset prices, and applying structured risk management can transform an intimidating gamble into an organized, long-term discipline. Sustainable wealth creation is rarely instantaneous; rather, it represents the cumulative result of prudent decisions carried out consistently across decades.
Key takeaways
- Investing commits capital into productive assets to earn returns and safeguard purchasing power against the erosive effects of inflation over time.
- Core investment vehicles include individual stocks, debt-based bonds, professionally managed mutual funds, and intraday-traded exchange-traded funds (ETFs).
- Strategic asset allocation sets the broad distribution of capital across asset classes, while diversification spreads risk across sectors and issuers within those classes.
- Higher potential returns inherently require accepting greater risk and wider variations in performance, though taking on risk does not guarantee a profitable outcome.
- Long-term success depends on avoiding common psychological traps, minimizing fund expense ratios, and maintaining realistic expectations across complete market cycles.
The economic case for investing capital
The primary reason people look beyond traditional cash storage is the economic reality that money loses purchasing power over extended periods. When savings sit entirely idle in physical cash or ultra-low-interest bank vaults, their real-world ability to buy everyday goods and services steadily diminishes due to the upward march of general living costs. Putting funds to work in productive financial assets counteracts this ongoing erosion by directing capital into commercial enterprises, municipal infrastructure, and global innovations that yield compounding returns.
From a historical standpoint, the modern investment landscape emerged directly from the capital requirements of expanding enterprises and national governments. When businesses needed to construct major transit lines, launch global trading operations, or develop municipal utilities, single private lenders or traditional banking entities could rarely shoulder the entire financial burden alone. To solve this problem, institutions began dividing their funding needs into fractional debt and equity instruments offered directly to the public.
In exchange for supplying this vital upfront liquidity, everyday individuals gained a mechanism to share in the operational prosperity and net profits generated by these commercial ventures. Today, that basic arrangement underpins international financial exchanges. Anyone with modest discretionary savings can participate alongside institutional players in supporting broader economic expansion, capturing a portion of global productivity rather than watching their stored cash decline in real value.
Core investment vehicles: How assets generate returns
Before purchasing any financial asset, an investor must understand what that asset legally represents, how it produces a cash flow or capital appreciation, and what factors determine its ongoing market valuation. The primary asset classes available to everyday investors feature distinct mechanics, risk profiles, and historical return trajectories.
Stocks
Stocks, also known as equities, represent fractional ownership shares in a corporate business. When you purchase a share of stock, you acquire a genuine equity stake in that enterprise, making you a part-owner of its underlying assets, intellectual property, and future profits. If the underlying company broadens its customer base, improves operational efficiencies, and increases net revenue, market demand for its equity increases, enabling you to sell the share at a higher price than you initially paid. Furthermore, established corporate boards may choose to return a portion of surplus earnings directly to investors via regular dividend payments.
Because corporate fortunes can scale dramatically alongside economic growth, stocks historically provide substantial long-term returns. However, corporate equities also carry high levels of price volatility and business risk. If an enterprise faces aggressive competition, poor managerial execution, unfavorable regulatory interventions, or severe macroeconomic downturns, the valuation of its equity can collapse rapidly, potentially leaving shareholders with severe losses.
Bonds
Bonds are fixed-income debt securities issued by corporations, municipal entities, or national treasuries. Rather than acquiring an ownership interest in an issuing organization, a bond purchaser steps into the role of a creditor or lender. The entity issuing the bond promises to repay the original principal loan balance on a predefined maturity date, while providing predictable, recurring interest payments—often referred to as coupon payments—throughout the lifespan of the loan.
Because governments and corporations are legally obliged to service their debt obligations before distributing any earnings or assets to equity owners, bonds are considered less risky than stocks. They are primarily favored by conservative investors and individuals nearing milestone events who prioritize dependable, predictable income streams and capital preservation over rapid balance-sheet growth. However, bonds still encounter sensitivity to interest rate fluctuations and the fundamental creditworthiness of the debtor.
Mutual funds
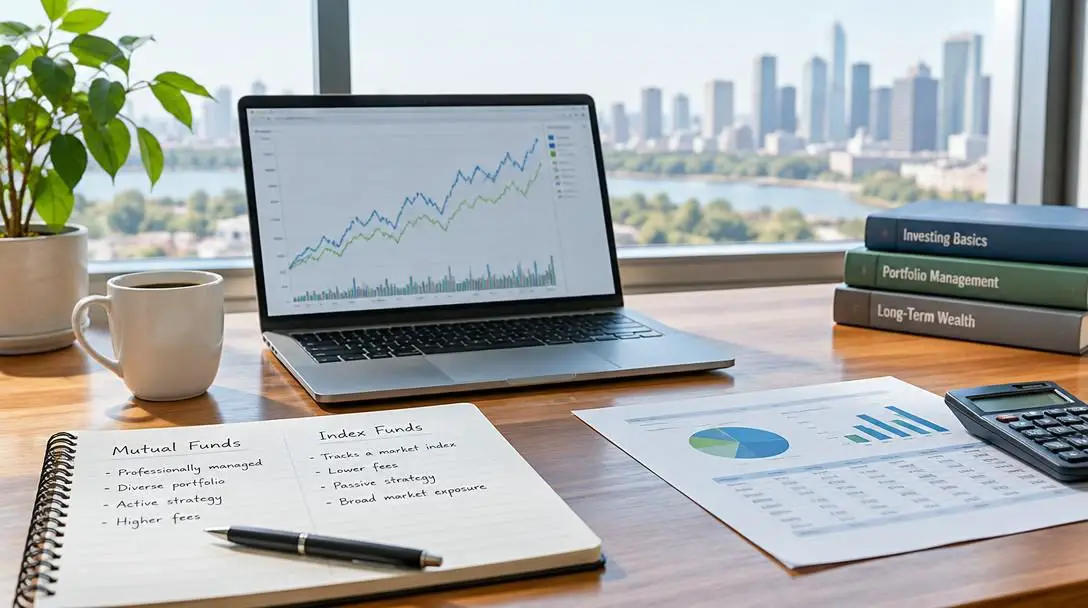
A mutual fund is an investment vehicle that aggregates capital from thousands of retail and institutional participants to purchase an extensive collection of individual stocks, bonds, or related financial instruments. Instead of requiring you to evaluate and purchase dozens of individual securities manually, the mutual fund pools communal capital into a unified portfolio administered by a professional asset manager or investment firm.
The lead manager actively selects, monitors, and adjusts the portfolio holdings in alignment with the fund's declared mandate, whether targeting rapid growth, high dividend yields, or broad index replication. This structure provides instant diversification, permitting even small deposits to gain fractional exposure across multiple industrial sectors and balance sheets that would otherwise prove prohibitively complex or expensive for an individual to assemble independently.
Exchange-traded funds (ETFs)
Exchange-traded funds share many structural similarities with conventional mutual funds in that they hold diversified baskets of underlying securities such as equities, commercial debt instruments, or physical commodities. However, exchange-traded funds differ fundamentally in their settlement mechanics and trading structure. While mutual fund transactions are tallied and settled precisely once per business day after the close of regular market hours, an ETF trades like a standard corporate stock on an open exchange.
Because ETFs trade continuously on secondary markets, investors can purchase or sell shares at live, prevailing prices throughout normal operating hours. This design blends the defensive risk-reduction advantages of a broad investment pool with the liquidity, order flexibility, and transparent price discovery characteristic of individual equity securities.
| Asset Class | Ownership Structure | Primary Income / Gain Mechanism | Relative Risk Profile | Trading Flexibility |
|---|---|---|---|---|
| Stocks | Direct equity ownership | Capital appreciation and corporate dividends | High risk and high volatility | Intraday on public exchanges |
| Bonds | Creditor debt obligation | Contractual periodic interest and principal return | Lower risk relative to equity | Secondary bond markets or via funds |
| Mutual Funds | Pooled collective share | Proportional share of net portfolio performance | Moderate, determined by underlying assets | Calculated once daily at market close |
| Exchange-Traded Funds | Pooled collective share | Proportional share of net portfolio performance | Moderate, determined by underlying assets | Intraday on public exchanges |
Managing risk through allocation and diversification
Managing an investment portfolio requires deliberate structural design rather than haphazard purchases driven by headlines. Two pillars govern how rational investors arrange their financial resources: asset allocation and portfolio diversification. Although beginners often treat these terms as interchangeable synonyms, they refer to distinctly different tiers of risk containment.
Asset allocation involves dividing an overall portfolio across fundamentally different asset classes, such as equities, fixed-income debt, and liquid cash equivalents. Every broad asset class reacts differently to changes in consumer spending, inflationary pressures, and monetary policy. During buoyant expansions characterized by heavy industrial output, corporate equities often deliver outsized capital gains while fixed-income products offer subdued outcomes. Conversely, during sudden contractions or sharp stock corrections, the contractual obligations of bonds and the liquidity of cash assets provide crucial balance. By choosing an appropriate baseline ratio of these primary asset buckets, you set the overarching stability of your accumulated net worth.
Diversification operates within each asset class, spreading your assigned capital across numerous individual entities, sectors, and geographic environments. Allocating sixty percent of your money to equities does not constitute sound risk management if that entire sum is committed to a solitary software company or one retail firm. True diversification spreads equity holdings across healthcare, energy, industrial manufacturing, consumer staples, and financial institutions.
True diversification means structuring a portfolio so that no single market failure can dismantle your broader financial health.
The governing principle of diversification is straightforward: it minimizes vulnerability by avoiding the dangerous practice of placing all your capital into a single basket. When an individual corporation fails, faces accounting scandals, or collapses under sudden competition, an extensively diversified portfolio absorbs the shock easily because the healthy performance of dozens of unrelated assets offsets the isolated loss.
The fundamental relationship between risk and return
A non-negotiable law of financial systems is that potential investment reward is bound directly to underlying investment risk. Every financial vehicle operates along this continuum; completely risk-free vehicles offering high rewards simply do not exist. Deploying capital always forces the investor to accept some mathematical probability of price swings, extended underperformance, or total loss of principal.
In general, higher-risk assets must offer higher prospective returns to entice participants to commit their funds. Because small emerging businesses and volatile tech firms operate in unstable competitive environments, investors require the potential for substantial upside before agreeing to assume that exposure. By contrast, a federal government holding legal taxation authority presents minimal default risk, meaning its debt securities offer much lower, more modest yields.
Crucially, an investor must recognize that accepting significant volatility does not ensure that profitable windfalls will actually materialize. Elevated risk merely widens the corridor of possible outcomes—creating scenarios that could yield superior returns, but equally could lead to steep capital loss. Your personal balance between safety and growth should depend on your specific time horizon, liquidity requirements, and emotional capacity to endure market corrections without making rash, panicky exits.
A practical roadmap to building your portfolio
Transitioning from financial theory to real-world investing requires a methodical framework. Taking systematic, sequential actions keeps novice investors focused on sound fundamentals rather than market noise.
- Conduct foundational research by reviewing educational resources provided by platforms and reputable financial institutions to understand market terminology, basic account types, and underlying asset behaviors.
- Establish defined financial goals by documenting your target time horizon, whether you are accumulating long-term retirement capital decades away or setting aside funds for a property down payment within a few years.
- Select your account infrastructure by deciding between a self-directed brokerage account for hands-on control, a certified financial advisor for tailored guidance, or an automated online investment platform that builds algorithm-driven portfolios based on your personal profile.
- Implement a consistent funding strategy by setting up automated, recurring transfers from your regular income, which systematically eliminates emotional friction and enforces steady discipline.
- Construct a broadly diversified baseline core by purchasing low-cost index-tracking exchange-traded funds or mutual funds that spread exposure across hundreds of enterprises across multiple business sectors.
- Schedule regular portfolio maintenance to review your asset allocation annually, rebalancing asset ratios whenever natural market movements drift your holdings away from your target risk profile.
Common investment pitfalls and how to avoid them
The psychology of market participants often presents a greater hazard to wealth accumulation than the actual movements of underlying asset prices. Novice investors frequently succumb to cognitive biases driven by greed during market euphoria or fear during downturns. Being aware of the standard mistakes made by beginners protects your capital from catastrophic, avoidable blunders.
- Investing in vehicles you do not understand: Committing funds to complex products, speculative instruments, or trending corporate tickers without examining how they generate cash flow is dangerous. If you cannot explain an asset's revenue model, balance sheet quality, and competitive moat in clear terms, avoid risking your capital in it.
- Failing to diversify across asset classes and sectors: Concentrating large percentages of capital into a single high-profile firm, one localized real estate market, or a single cyclical sector leaves your wealth exposed to sudden disruptions, catastrophic managerial errors, and industry-specific obsolescence.
- Harboring unrealistic expectations of rapid gains: Treating financial markets as modern lotteries or get-rich-quick mechanisms leads directly to erratic risk-taking, premature disappointment, and buying at the absolute peak of speculative frenzies. Investing is a marathon that relies on steady compounding over full market cycles.
- Attempting to predict short-term price fluctuations: Trying to day-trade or time market peaks and valleys rarely succeeds over sustained periods. Reactive trading usually causes retail participants to panic-sell near market bottoms out of fear and purchase assets only after significant upward moves have already taken place.
Long-term considerations: Expenses and portfolio maintenance
As you gain experience as an active participant in the market, your attention must turn toward managing operational details that silently dictate your real net returns over time. Two critical factors that compound over multiple decades are fund management fees and portfolio upkeep costs.
Every mutual fund and exchange-traded fund incurs administrative overhead, trading fees, and advisory expenses, which are bundled into an annual metric known as the expense ratio. This percentage is deducted directly from fund assets regardless of whether the fund posts a net gain or a net loss for the year. While an extra fraction of a percentage point may seem inconsequential in an isolated twelve-month span, that seemingly tiny deduction compounds over thirty or forty years, consuming tens of thousands of dollars in prospective gains. Favoring cost-effective, transparent fund structures guarantees that the vast majority of your returns remain parked in your balance sheet.
Furthermore, maintaining your portfolio requires mindful rebalancing. As certain sectors or equity components surge during economic booms, they naturally begin to comprise an outsized share of your total portfolio value. Left unaddressed, your exposure drifts steadily toward high-risk assets right as they become expensive. Periodically trimming assets that have grown beyond their assigned targets and redeploying that capital into lagging or stabilizing asset classes restores your desired balance, enforcing the disciplined habit of selling high and buying low.
Frequently asked questions
How much money do I need to start investing?
Modern online investment platforms, brokerage firms, and fractional share programs make it possible to begin investing with very modest sums. You no longer require thousands of dollars to build an initial portfolio, as broad-market index ETFs and fractional shares can be acquired for nominal amounts.
What is the difference between saving and investing?
Saving involves parking cash in safe, liquid accounts for short-term goals and emergency expenses, yielding little return. Investing involves deploying capital into productive assets like stocks and bonds to generate compound growth and beat inflation over an extended time horizon.
Why shouldn't I keep all my money in cash?
Holding all your assets in physical cash or ultra-low-interest accounts exposes your capital to inflation risk. Over time, the purchasing power of idle money declines as prices for everyday goods, housing, and healthcare trend upward.
How do expense ratios impact long-term returns?
Expense ratios are ongoing management and operational fees deducted directly from a mutual fund or ETF's total assets. Over decades, even modest differences in expense ratios compound significantly, siphoning away substantial portions of your final wealth.
What is the main difference between mutual funds and ETFs?
While both represent diversified pools of underlying securities, mutual funds are priced and traded only once per business day after markets close, whereas ETFs trade continuously throughout regular trading hours on open exchanges just like individual company shares.
The bottom line
Investing is not an exclusive domain reserved for institutional managers or market insiders; it is a universally accessible financial framework capable of transforming personal earnings into lasting security. The journey begins with mastering fundamental distinctions: understanding the functional mechanics of equities versus fixed income, utilizing broad asset allocation and diversification to limit downside exposure, and aligning your portfolio's risk profile with your personal time horizon.
By establishing clear goals, keeping fund expenses low, and refusing to surrender to short-term market hysteria, you can construct an enduring strategy designed to navigate changing economic conditions. Markets will inevitably experience short-term cycles of volatility and contraction, but deliberate, disciplined capital deployment across well-diversified assets remains the proven pathway toward achieving true financial autonomy.