
Financial Planning 101: A Guide to Make Sense of Your Finances
Financial planning is the comprehensive process of evaluating your current financial situation, identifying meaningful personal goals, and designing a realistic strategy to achieve those objectives. Whether you are just beginning your professional career or are already well into your peak earning years, engaging in structured financial planning is essential to make sense of day-to-day cash flow and build enduring financial stability.
Personal finances rarely remain static over time. Household income changes, everyday living expenses fluctuate, and long-term priorities naturally shift as major life milestones draw closer. Without an intentional approach, managing money easily devolves into a reactive cycle where financial decisions are made only when an unexpected emergency happens or a stressful bill arrives. Financial planning replaces this short-term coping with long-term preparation, organizing your money into a cohesive system that reflects your values and protects your future.
Key takeaways
- Financial planning functions as an interconnected system balancing day-to-day cash flow, defensive reserves, and long-term wealth accumulation.
- A thorough baseline assessment requires cataloging four core pillars: income, expenses, assets, and debts.
- Defining targets using the SMART framework ensures that short-term wishes and long-term retirement visions remain measurable and achievable.
- Maintaining an emergency fund with three to six months of expenses protects you from high-interest debt when sudden shocks arise.
- Sustainable wealth creation requires disciplined debt payoff strategies paired with diversified investments tailored to your individual risk tolerance.
How the financial planning system works
At its heart, financial planning works as an interconnected system where every decision reverberates across your broader financial life. The money brought home from primary wages or side ventures directly determines what can be committed toward debt reduction, daily living, or long-term growth. When you alter one variable in the system—such as increasing discretionary leisure spending—you directly influence the resources available for emergency savings or investment vehicles.
The foundation of this mechanism is net income, calculated by comparing incoming cash flow to outgoing obligations. When earnings exceed living costs, the resulting positive net income provides the financial fuel to accelerate debt payoffs, build liquid reserves, and acquire productive assets. Conversely, a negative net income drains existing savings and expands debt, undermining stability.
The system operates in sequential phases, prioritizing present defensive security before transitioning toward aggressive wealth accumulation. Debt management and emergency reserves serve as defensive armor; once those safeguards are active, resources flow toward compounding assets like stocks, bonds, and mutual funds. Because life circumstances shift, financial planning operates as an ongoing feedback loop of regular review and recalibration.
Treating money as an organized system rather than a collection of random transactions transforms financial stress into lasting security.
Assessing your financial situation
Before mapping out future destinations, you must establish an honest baseline of your starting coordinates. Assessing your current standing requires evaluating four distinct financial categories: income, expenses, assets, and debts.
| Financial Pillar | Primary Components | Role in Your Plan |
|---|---|---|
| Income | Wages, salaries, investment dividends, interest, freelance projects | Supplies the incoming cash flow that funds living costs, savings, and investments. |
| Expenses | Housing, utilities, groceries, transportation, leisure, discretionary costs | Determines your baseline cost of living and reveals opportunities to capture surplus cash. |
| Assets | Checking accounts, savings balances, retirement accounts, vehicles, real estate | Represents economic value owned outright or accumulated to build net worth. |
| Debts | Credit cards, personal loans, auto financing, student loans | Identifies legal liabilities and financing charges that drain monthly cash flow. |
Tracking expenses requires distinguishing between fixed necessities—such as rent, mortgage obligations, utility services, and basic groceries—and variable discretionary spending like entertainment or lifestyle upgrades. Similarly, cataloging liabilities from revolving credit cards to structured student loans ensures no financing costs escape notice.
Setting financial goals with the SMART framework
Clear goals provide the motivation and framework needed to guide daily spending habits. Without concrete targets, it is easy to surrender to impulse spending. Goals generally divide into two distinct timelines:
- Short-term goals: Objectives targeted for completion within months or up to two years, such as saving for an upcoming vacation or paying off a revolving credit card balance.
- Long-term goals: Sustained commitments spanning multiple years or decades, such as accumulating a down payment for a home or systematically funding a retirement portfolio.
To prevent these aspirations from remaining abstract wishes, translate them through the SMART framework:
- Specific: Define the exact outcome. Instead of resolving to "save more money," articulate a goal to "save funds for a home down payment."
- Measurable: Attach a precise dollar amount so that progress can be monitored objectively over time.
- Achievable: Choose a milestone that fits realistically within your baseline income and expense structure to prevent burnout.
- Relevant: Align each goal with your core personal values, lifestyle requirements, and broader financial security.
- Time-bound: Anchor the target to an explicit completion date, establishing healthy urgency and focus.
Developing and managing an operational budget
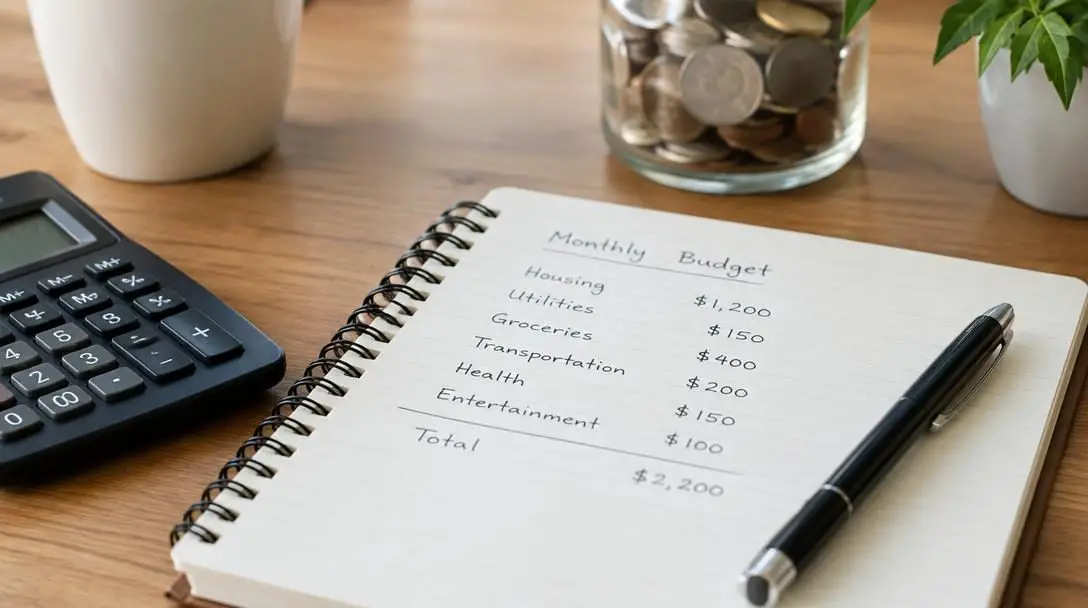
A budget is the operational engine that translates your overarching goals into daily execution. Far from an exercise in deprivation, a well-structured budget grants permission to spend intentionally on the things that matter most while curtailing unexamined waste. It tracks actual cash flow over a set monthly or annual cycle.
The budgeting process starts by subtracting total living expenses from aggregate monthly income, resulting in one of two financial realities:
- Positive net income: Income exceeds total expenses, creating a surplus. This surplus can be routed intentionally toward high-interest debt payoffs, emergency savings, or long-term investment assets.
- Negative net income: Expenses outpace earnings. This imbalance signals immediate danger, requiring proactive measures to reduce discretionary spending, boost incoming cash flow, or both, until equilibrium is restored.
Step-by-step guide to building your financial plan
Transforming financial concepts into practical routines requires an orderly, sequential approach. Navigating the process step by step keeps you from feeling overwhelmed by account balances and statements.
- Gather all primary financial documents: Assemble recent pay stubs, bank statements, credit card bills, investment portfolios, and loan balances.
- Calculate your net baseline: Total all reliable monthly revenue and subtract your living expenses to establish whether you operate with positive or negative net income.
- Formalize your SMART targets: Document concrete short-term milestones alongside your multi-year priorities, attaching specific dollar amounts and timelines to each.
- Draft your functional budget: Allocate every expected dollar toward essential living necessities, debt reductions, reserve contributions, or planned discretionary spending.
- Establish an emergency reserve: Open a dedicated savings account and deposit funds systematically until you hold three to six months' worth of essential living expenses.
- Target high-interest liabilities: Inventory debts by interest rate, channeling extra cash toward the most expensive balances while exploring low-rate consolidation options.
- Initiate an investment program: Assess your personal risk tolerance and route regular capital into diversified assets like stocks, bonds, and mutual funds.
- Review and adjust periodically: Audit monthly expenditures against your budget and conduct periodic reviews of your investment portfolio to keep allocations aligned with your needs.
Building your emergency fund
An emergency fund provides the essential defensive buffer needed to absorb sudden financial shocks. Life contains unavoidable surprises: an unexpected medical bill, an urgent vehicle repair, or an unpredicted household maintenance crisis. Without liquid cash readily available, individuals are often forced to take on high-interest credit card balances or raid long-term investments, setting back years of progress.
Financial standards recommend holding three to six months' worth of essential expenses in a secure, liquid account. For someone starting with minimal savings, this aggregate figure can feel intimidating. However, establishing this reserve does not require an immediate windfall. By setting aside modest, regular contributions each month, you gradually assemble a robust financial shield that preserves peace of mind.
Managing debt effectively
Uncontrolled liabilities erode wealth by consuming valuable monthly cash flow through compounding interest charges. Taking control of what you owe requires an active, structured repayment strategy.
Start by compiling a complete list of all outstanding balances, noting their respective annual percentage rates. Directing surplus payments toward the highest-interest debt first allows you to eliminate the most expensive balances rapidly, drastically cutting total financing charges over the life of the loans.
Throughout your debt repayment phase, ensure that every minimum required payment across all accounts is submitted on time. Crucially, commit to avoiding new revolving debt while you work down existing obligations, ensuring that your net liabilities steadily decline.
Investing for future wealth accumulation
While disciplined budgeting and debt reduction protect your finances today, structured investing is the mechanism that accumulates long-term wealth and finances retirement. Keeping all surplus money in cash accounts exposes your capital to the gradual erosion of purchasing power. Investing enables your capital to outpace living costs over decades.
Before committing funds, it is essential to identify your personal risk tolerance—your emotional and financial ability to endure short-term market declines. With an understanding of your risk profile, you can construct a diversified portfolio across three core asset categories:
- Stocks: Equity investments representing partial ownership in operating corporations, offering strong long-term growth potential accompanied by price volatility.
- Bonds: Fixed-income securities issued by governmental bodies or corporations that pay structured interest returns over designated periods, dampening overall portfolio swings.
- Mutual funds: Pooled investment vehicles that combine capital across a broad basket of individual securities, granting immediate diversification within a single holding.
Spreading capital across multiple asset classes mitigates the danger of relying on any single asset's performance. As you age, transition into different career phases, or experience changing risk preferences, your portfolio should be systematically reviewed and rebalanced to maintain appropriate allocations.
Common financial planning mistakes to avoid
Even motivated planners can run into unforced errors that derail their progress. Remaining watchful against these frequent traps keeps your long-term plan moving forward:
- Overlooking small, variable expenses: Ignoring occasional coffees, takeout meals, or irregular auto upkeep quickly consumes surplus cash flow and unbalances your monthly budget.
- Delaying action for a major windfall: Waiting to start an emergency reserve or investment plan until you have large sums wastes years of compounding growth. Small monthly contributions yield significant results over time.
- Using emergency reserves for lifestyle spending: Treating a dedicated emergency fund as an auxiliary account for vacations or luxury purchases leaves you completely exposed to genuine crises.
- Paying only minimum debt balances: Submitting bare minimum payments on high-interest credit cards guarantees that the majority of your payment feeds financing fees rather than lowering principal.
- Misjudging personal risk tolerance: Selecting an investment strategy that is either too aggressive or overly conservative can result in panic-selling during market dips or missing required growth targets.
- Failing to update the plan: Treating a financial plan as a static document created once and forgotten prevents your strategy from keeping pace with promotions, family additions, or new priorities.
Frequently asked questions
How much money do I need to start financial planning?
You do not need a large sum of money to begin financial planning. The process starts with assessing your current income, tracking expenses, and establishing an initial budget. Consistent, modest monthly contributions toward savings and debt reduction build strong financial security over time.
How large should an emergency fund be?
Financial guidelines recommend accumulating at least three to six months' worth of essential living expenses. This fund should be stored in an accessible, liquid account dedicated exclusively to unforeseen disruptions such as medical emergencies or vital car repairs.
What is the difference between short-term and long-term financial goals?
Short-term goals are objectives you plan to complete within months or up to two years, such as saving for a vacation or clearing a credit card balance. Long-term goals require sustained funding over many years or decades, such as purchasing a home or building an investment portfolio for retirement.
Why should I invest in stocks, bonds, and mutual funds instead of keeping cash?
Holding all your assets in cash leaves your wealth vulnerable to the gradual loss of purchasing power over extended periods. Investing across diversified asset classes like stocks, bonds, and mutual funds allows your capital to generate returns and build wealth to meet long-term goals.
How often should I review my financial plan?
You should review your budget monthly to track actual spending against your targets. Evaluate your debt reduction progress and emergency reserves on a quarterly schedule, and conduct a thorough annual assessment of your investment portfolio to ensure it continues to match your risk tolerance and goals.
The bottom line
Financial planning is not a one-time project that ends once a spreadsheet is completed; it is an ongoing personal discipline that evolves alongside your life. By conducting an unvarnished audit of your income, expenses, assets, and liabilities, you replace uncertainty with clarity. Translating your hopes into specific SMART goals and operational budgets gives every dollar purposeful direction.
As you build your emergency reserves, systematically eliminate high-interest liabilities, and route steady contributions into diversified investments, your financial security deepens. Maintain a recurring schedule to audit your budget monthly and rebalance your investment portfolio periodically. By viewing personal finance as a dynamic, manageable system, you protect yourself against life's unexpected disruptions while steadily constructing lasting financial independence.




