Understanding Events and Probabilities with Poisson Distribution
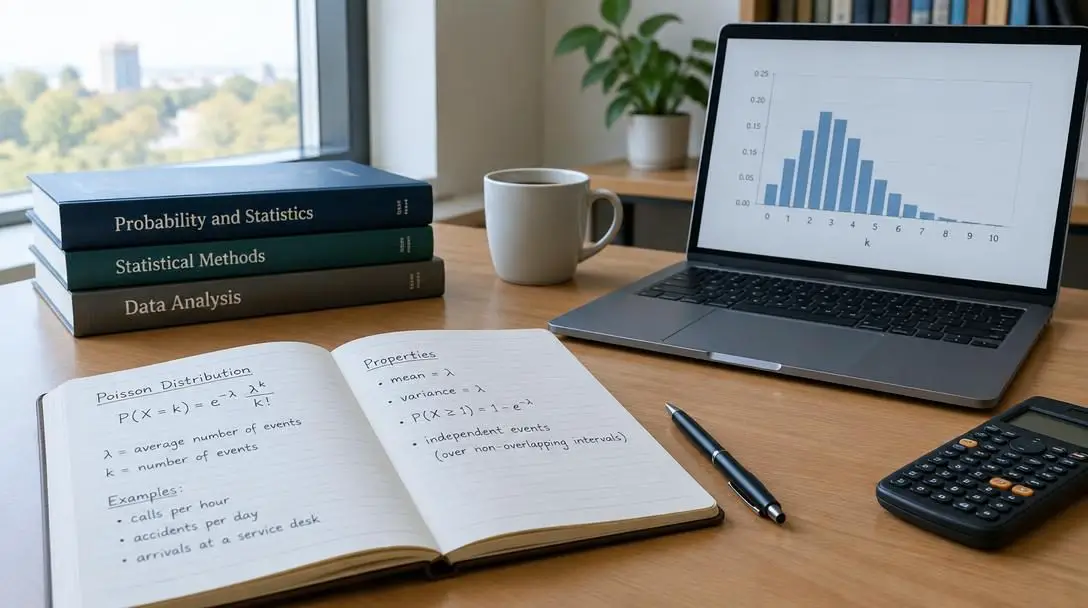
In statistical analysis, quantifying how frequently unusual incidents occur is a central challenge for planners, researchers, and engineers. The Poisson distribution provides a mathematical framework to evaluate the probability of a specific count of events happening within a defined interval of time or space. Rather than forcing analysts to guess how often rare occurrences might materialize, this model translates historical frequencies into concrete, actionable probabilities.
Named after the French mathematician Siméon Denis Poisson, who introduced the concept in the early 19th century, the distribution has evolved into a cornerstone model across fields such as biology, finance, and industrial engineering. By establishing expected frequencies across discrete observation windows, organizations can better understand operational risks, optimize resource allocation, and identify when systems begin to deviate from normal operational behavior.
Key takeaways
- The Poisson distribution calculates the probability of a specific number of independent events occurring across a fixed time or space interval.
- A single parameter, lambda (λ), represents the average arrival rate and completely dictates the center and shape of the probability model.
- The model relies on two strict assumptions: events must happen at a constant average rate and must occur entirely independently of one another.
- Analysts can scale the rate parameter proportionally when expanding or contracting the observation timeframe, such as converting daily occurrences into weekly baselines.
Historical origins and conceptual foundations
Before Siméon Denis Poisson introduced his formulation in the early 19th century, standard probability theory concentrated primarily on structured games of chance. Analysts routinely evaluated rolls of dice or coin tosses where the total number of attempts was fixed, discrete, and easily counted. In such discrete settings, traditional combinatorial calculations allowed mathematicians to evaluate the odds of winning or losing across a predetermined run of trials.
Real-world phenomena, however, rarely conform to a rigid series of separate trials. Analysts frequently observe continuous spans—such as hours on an assembly line, square miles of forest canopy, or miles of highway—where the exact number of opportunities for an incident to occur cannot be divided into distinct attempts. Poisson bridged this mathematical gap by designing a model tailored specifically for count data measured over continuous intervals. Rather than tracking how many total attempts were made, his framework measured the rate of occurrence across a given continuous medium.
Over the subsequent decades, researchers across biological and physical disciplines recognized the utility of this model. It allowed scientists to analyze isolated phenomena—from microscopic cell counts in biology to structural equipment breakdowns in engineering—without requiring a predefined ceiling on the total possible number of trials.
Core mathematical mechanics and the formula
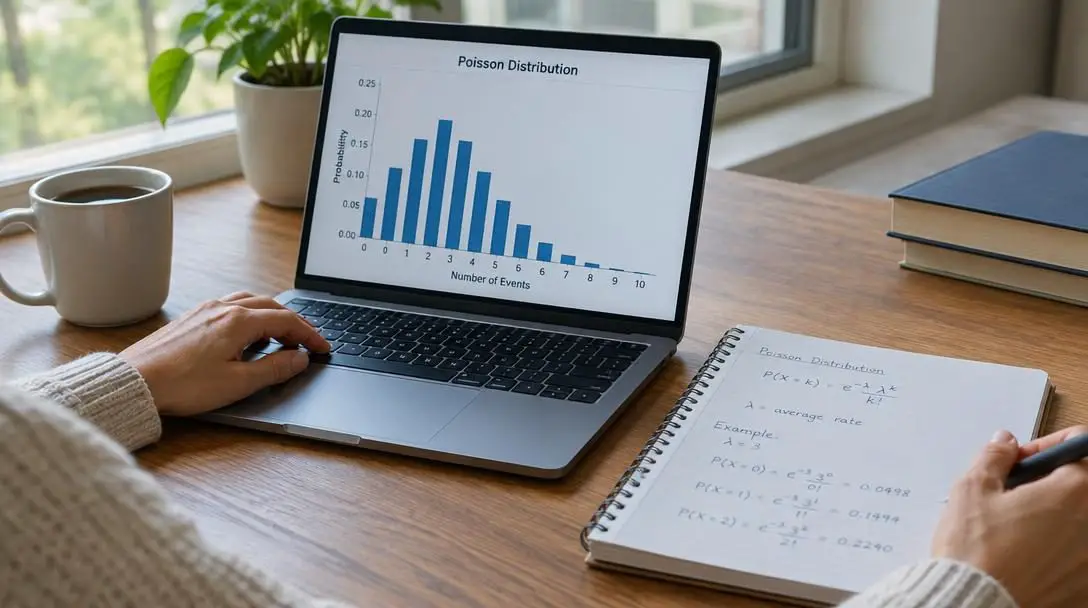
The defining structural attribute of the Poisson distribution is that it requires only one parameter: lambda (λ). This parameter represents the average rate of occurrence or the expected number of events within the chosen window. Because λ serves as the focal point of the distribution, establishing an accurate baseline rate is the essential starting point for all downstream calculations.
The probability of observing exactly k events in a designated window of time or space is expressed through the following formula:
P(k) = (e^(-λ) * λ^k) / k!
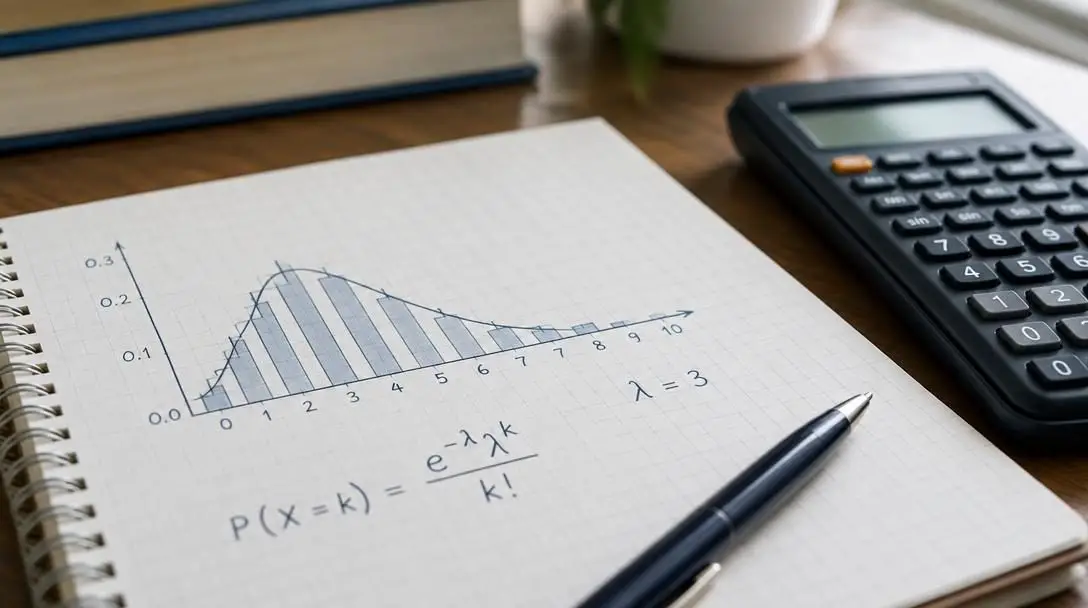
To apply this formula accurately, analysts must understand the four distinct mathematical components that govern the calculation:
- k: The specific integer target for the number of occurrences being evaluated (such as 0, 1, 2, or 5).
- λ (lambda): The average or expected frequency of events calibrated precisely to the observation interval.
- e: Euler's constant, a mathematical constant approximately equal to 2.71828.
- k! (k factorial): The product of all positive integers less than or equal to k (for instance, 5! = 5 * 4 * 3 * 2 * 1 = 120, with 0! defined mathematically as 1).
Real-world calculation scenarios
To see how the formula works in an operational environment, consider a manufacturing facility where historical data indicates that an assembly line produces an average of 3 defective parts per hour. In this scenario, the expected baseline rate λ is equal to 3. If a quality control supervisor wants to calculate the precise likelihood that a future one-hour shift will yield exactly 5 defective parts, the formula is populated as follows:
P(5) = (e^(-3) * 3^5) / 5!
In this calculation, 3 raised to the fifth power equals 243, while 5 factorial (5!) evaluates to 120. Multiplying 243 by e^(-3) (which is approximately 0.049787) and dividing the result by 120 yields approximately 0.1008. Consequently, the probability of detecting exactly 5 defective parts in that one-hour period is approximately 10.08%.
Another major advantage of the model is its flexibility across different time horizons. Because λ must correspond directly to the specific duration under evaluation, the parameter scales proportionally when the window shifts. For example, if a regional transit authority records a historical average of 2 traffic accidents per day along a specific corridor, the daily rate is λ = 2. If the planners want to evaluate accident risk across a full seven-day week, they adjust the rate parameter:
λ = 2 accidents per day * 7 days per week = 14 accidents per week
Using λ = 14, the team can determine the probability of experiencing zero accidents, 14 accidents, or severe spikes across any given week, giving planners an objective baseline for emergency response deployment.
| Operational scenario | Baseline rate (λ) | Target events (k) | Interval scope | Key application |
|---|---|---|---|---|
| Manufacturing quality control | 3 defects per hour | 5 defects | Single one-hour shift | Evaluating unexpected defect spikes |
| Regional traffic safety | 2 accidents per day | 14 accidents | Seven-day calendar week | Resource and emergency team allocation |
| Biological sample testing | Variable cell count | Target integer | Defined microscopic grid | Quantifying organism concentration |
Key assumptions and underlying mechanics
While the mathematical execution of the formula is straightforward, the validity of its results depends on two foundational assumptions. First, the model assumes that events occur independently. This means the arrival of one event cannot alter the probability of future occurrences. Second, the distribution requires that the average arrival rate remains constant over time throughout the observation window.
When the assumption of event independence collapses, standard probabilities become unreliable and can mask critical system deterioration.
In many real-world environments, these assumptions face severe pressure. Consider again the manufacturing facility producing machine parts. If a lathe begins producing defective components due to thermal wear, the presence of the first defect dramatically increases the likelihood that subsequent defects will follow. The events cease to be independent; instead, they cluster together as symptoms of an unaddressed mechanical failure.
Similarly, traffic accidents may not remain independent if a primary collision blocks lanes and creates visual distractions that trigger secondary collisions. In circumstances where underlying mechanisms cause occurrences to bunch together or accelerate, the standard Poisson distribution understates the risk of multi-event clusters. When independence breaks down, statisticians must deploy alternative models capable of accounting for correlation and root-cause mechanics.
Step-by-step guide to applying the distribution
When implementing the Poisson framework to analyze rare events or operational counts, analysts should follow an orderly series of diagnostic and computational steps:
- Define the observation interval: Establish clear boundaries for the continuous window of interest, specifying whether the scope is a temporal interval (such as an hour, day, or week) or a spatial region (such as a square foot, an acre, or a volume of fluid).
- Determine the baseline rate (λ): Gather historical data to identify the average number of occurrences within the defined window, making sure to scale the rate up or down proportionally if the length of the window changes.
- Verify the core assumptions: Inspect the operational environment to confirm that occurrences do not influence one another and that the arrival rate remains reasonably stable throughout the evaluation window.
- Select the target count (k): Choose the specific integer number of occurrences you wish to assess, whether that is zero occurrences to evaluate total reliability or high values to evaluate overflow risk.
- Calculate the probability: Substitute λ, k, and Euler's constant into the formula P(k) = (e^(-λ) * λ^k) / k! to compute the exact probability value.
- Interpret the results for decision-making: Convert the resulting decimal into a clear percentage to determine reserve capacities, adjust quality control thresholds, or identify anomalous patterns.
Common pitfalls to avoid
Even though the Poisson distribution features only one parameter, analytical oversights can lead to invalid conclusions. Reviewing frequent modeling mistakes helps preserve analytical rigor:
- Mismatched interval units: Applying a daily baseline rate to an hourly calculation without dividing by 24 invalidates the mathematics. Always confirm that the units of λ match the timeframe of k.
- Ignoring event dependence: Assuming independence in systems prone to cascading failures—such as network server outages or machine degradation—causes severe underestimation of extreme events.
- Treating fluctuating rates as constant: Using a single average across an entire 24-hour cycle when daytime activity is ten times higher than nighttime activity leads to skewed probability forecasts.
- Applying the model to continuous variables: Attempting to use the formula on continuous measurements, such as weights, processing times, or monetary amounts, violates the requirement for discrete integer count data.
Frequently asked questions
What is the difference between lambda and k in the Poisson formula?
Lambda (λ) represents the historical average or expected rate of occurrences over a specific interval, while k represents the hypothetical number of events whose probability you want to calculate.
Can the target value k be a decimal number?
No. The Poisson distribution models discrete count data, meaning k must always be a non-negative whole integer such as 0, 1, 2, or higher.
How do you adjust the lambda parameter for different time periods?
Because the rate parameter scales proportionally, you multiply or divide the baseline rate to match the target interval, such as multiplying a daily rate of 2 accidents by 7 to yield a weekly rate of 14.
What happens to the calculation if events are not independent?
If events encourage or trigger each other—such as defects caused by a failing machine part—the Poisson model breaks down and alternative statistical methods that account for event correlation must be used.
Why is Euler's constant (e) used in the formula?
Euler's constant, approximately 2.71828, emerges naturally in probability when modeling continuous growth, decay, and the limiting behavior of discrete occurrences across continuous spans of time or space.
The bottom line
The Poisson distribution remains an indispensable analytical tool for modeling the probability of rare events across time and space. By distilling complex arrival processes down to a single parameter, it empowers professionals in finance, biology, and engineering to replace intuition with rigorous mathematical probability. However, its simplicity is also its primary constraint. Analysts must verify that events remain strictly independent and that arrival rates stay constant. When those criteria are satisfied, the model offers unmatched clarity for forecasting operational risk and planning future capacity.